3.9 Ethics and Financial Reporting
Incentives for unethical financial reporting, and the laws and professional codes that push back.
Part 1 of 3 Why the Temptation Exists
A business can misstate a financial report in two directions. A report that makes the business look better than it is can get a loan approved that a lender would otherwise refuse. The same report can improve the loan's terms or raise the share price. A report that makes the business look worse than it is cuts the tax bill. Understating income to cut taxes is tax evasion.
Financial reporting ethics covers both the keeping of the records and the reporting of the results. Financial statements exist so that a person who was never inside the business can rely on them. A misstated report makes the statements unreliable for that person.
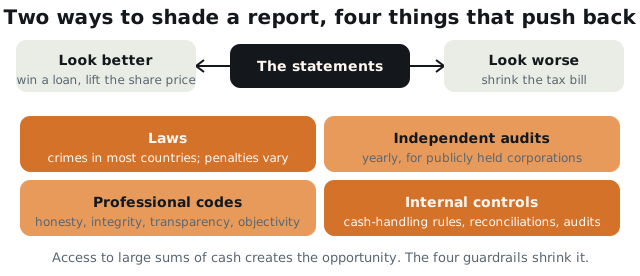
Cash creates a second kind of temptation. Where one person can reach large sums of a business's money, the chance exists to embezzle, to misuse funds or to falsify records for private gain. Access to large sums of a business's cash is what creates the opportunity.
Part 2 of 3 Six Unethical Practices
| Practice | What it is | At a drink shop |
|---|---|---|
| Misuse of funds | Spending money in a way that was never authorized | Paying a personal bill from the business account |
| Tax evasion | Illegally avoiding taxes owed | Understating income |
| Embezzlement | Secretly taking money entrusted to your care | Skimming the register |
| Bribery | Offering or accepting something of value to sway a decision | Paying an inspector to pass a failed inspection |
| Lack of transparency | Failing to communicate openly and honestly with people entitled to the information | Not telling a lender about a dispute |
| Fraud | Intentional deception for financial gain, including falsified financial statements | Booking next quarter's deposits as this quarter's revenue |
The hardest case to recognize uses only real numbers. A quarter closes with $38,000 of revenue, against $41,000 in the same quarter the year before, a 7.3% drop. Just after the quarter closes, $3,500 of real deposit checks arrive for events several months away. If the business counts the $3,500 of deposits inside the closed quarter, the quarter's revenue shows a 1.2% rise over the year before. Every dollar is real and the date is false. The business's own receivables line proves that the business records revenue when the work is done. A careful reader looks for a recording method that changes for one period to make the results look better.
Consistency is what makes a method honest. List the signed events, with their dates, as revenue to come.
Part 3 of 3 Four Safeguards Against Unethical Reporting
| Safeguard | What it does |
|---|---|
| Laws | Misuse of funds, tax evasion, embezzlement, bribery and fraud are crimes in most countries; statutes and punishments vary by country |
| Independent audits and market rules | U.S. law requires publicly held corporations to submit records yearly for audit by an independent accounting firm; financial market regulations give investors accurate information and protect them from fraud |
| Professional codes | Bodies for accountants and financial managers publish ethics codes built on honesty, integrity, transparency, objectivity and confidentiality |
| Internal controls | Codes of conduct, audit requirements, cash-handling rules: a written rule that deposits are recorded on the day of the event, a nightly count reconciled against the register |
The same rule of honest reporting applies to households. Overstating income on a rental application or a car loan application misstates a financial report. Overstated income on an application is fraud.
A good control makes a discrepancy visible.
Worked Examples
Reporting the quarter honestly
Compute a quarter-over-quarter change and pair it with the explanation a reader needs.
First-quarter revenue came in at $38,000 against $41,000 in the same quarter a year earlier. A street closure spanning the January and February line cost about $1,800 of sales in late January and about $1,200 in early February. Report the quarter.
- This quarter revenue
- $38,000
- Prior year quarter revenue
- $41,000
- Sales lost in late January
- about $1,800
- Sales lost in early February
- about $1,200
1. Find the change in dollars
$38,000 minus $41,000 is negative $3,000.
2. Divide by the prior-year figure
Negative $3,000 over $41,000 is negative 0.0732.
3. State it as a percentage
Multiply by 100 to reach negative 7.3%.
4. Account for the gap
Add the two closure figures. $1,800 plus $1,200 is $3,000, which is the entire year-over-year shortfall.
Check answerHide answer
Answer
negative 7.3%, fully explained by the closure. Revenue fell $3,000, or 7.3%, and a documented eight-day street closure accounts for the whole $3,000.
Why it matters
Honest reporting is not the same as silent reporting. Filing the true figure with a dated note explaining the disruption gives a reader more information than the shaded version would, not less.
Why moving real cash across a date line is still misleading
Compute the figure a shaded report would show and identify precisely what makes it wrong.
Four deposit checks totalling $3,500, being 50% deposits on $7,000 of signed spring events, arrive in the first week of April. The quarter being filed ended March 31 at $38,000. Compute what counting that cash inside the quarter would report.
- Honest quarter revenue
- $38,000
- Deposits received in April
- $3,500
- Prior year quarter revenue
- $41,000
- Events the deposits relate to
- May and June
1. Add the deposits into the closed quarter
$38,000 plus $3,500 is $41,500.
2. Compute the change that would be reported
$41,500 minus $41,000 is positive $500, and $500 over $41,000 is 0.0122.
3. Put the two results side by side
The same equation on the same business reports negative 7.3% honestly and positive 1.2% shaded. Nothing was invented; only a date moved.
4. Name why the shaded version misleads
The deposits are cash for work not yet delivered, and the receivables line on the same balance sheet proves the business records revenue when work is done, so the method would have changed for exactly one flattering quarter.
Check answerHide answer
Answer
positive 1.2%, and misleading. Counting April deposits inside the closed quarter turns a 7.3% decline into a 1.2% increase without inventing a single dollar.
Why it matters
This is the version worth studying, because every number in it is real. What makes it fraud is not fabrication, it is the period the money was assigned to, and the fact that the business abandoned its own established method to get there.
Key Terms
Practice Questions
6 questions. Nothing here is recorded or scored.
- Question 13.9.A.3
Lightwell Photography
Elise Navarro owns Lightwell Photography, a one-room portrait and wedding studio. Wedding clients book with a 50 percent retainer months in advance, and Elise's bookkeeping has always recorded a wedding's revenue on the day she shoots it. Weddings cluster in the summer, so her first quarter is thin: school portraits, a few family sessions, and the weekend mini-sessions her part-time assistant runs for cash at a folding table. Elise is applying for a bank loan to build out a second shooting room, and the bank has asked for her most recent quarterly statements. While she assembles them, retainer checks for six summer weddings arrive. She is weighing three moves: adding the retainer money to the first quarter's revenue line so the slow quarter looks stronger, spending part of the retainer money now on a lens she has wanted for a year, and skipping the count she usually runs at each mini-session, matching the sign-up sheet against the cash box, because the assistant has never come up short.
Which of the following best explains why Elise might be tempted to add the retainer checks to first-quarter revenue?
- A.Reporting higher revenue would lower the studio's taxes for the quarter.
- B.Portraying the studio as healthier than it is could win a loan or better terms.
- C.The retainers became earned revenue the moment the checks cleared the bank.
- D.Statements must include each payment received during the reporting period.
Check answerHide answer
Answer: B
- A.
- This points the lever the wrong way: higher reported revenue raises a tax bill. Understating income to shrink the tax bill is the other direction of the same dishonesty, and it has its own name, tax evasion.
- B.
- Correct. A business that portrays its financial situation as better than it really is can secure loans it might otherwise be denied, or better terms on them, and that is exactly what a padded revenue line offers Elise: a stronger-looking quarter in front of the one reader deciding on her loan.
- C.
- This fails on her own method. The studio records wedding revenue on shoot day, so a March check for a July wedding is July revenue whether or not the check has cleared.
- D.
- No such requirement exists, and it would erase the distinction the statement runs on: revenue is recorded when it is earned under the business's method, not whenever cash happens to arrive.
- Question 23.9.A.1, 3.9.A.2
Elise's idea of spending retainer money on the lens is best described as which of the following?
- A.Reinvestment of the studio's earned profit into new camera equipment for shoots.
- B.Embezzlement, because the business money would buy a personal item.
- C.Misuse of funds, because the retainers pay for work not yet performed.
- D.Tax evasion, because the purchase would lower the studio's reported income.
Check answerHide answer
Answer: C
- A.
- This fails at the first word. A retainer is unearned money, and profit only exists after work is delivered and costs are paid.
- B.
- The closest neighbor in this topic's vocabulary. Embezzlement is a person entrusted with a business's money secretly taking it for personal gain, a bookkeeper skimming an account she manages. Elise owns the studio and the lens purchase would sit in the open in her own records; the wrong here is timing, spending before earning.
- C.
- Correct. A retainer is a client's money held against a future wedding: cash in hand today, revenue only when the work happens. Spending it early puts unearned money into gear the studio keeps, and if a wedding cancels or moves, the money owed back has already left. That is misuse of funds, and it commits the same wrong the padded revenue line commits on paper: both treat money that belongs to the future as if the business had already earned it.
- D.
- Tax evasion understates what the business earned so the government collects less. Buying a lens with retainer money misuses client funds; it hides no income and aims at no tax bill.
- Question 33.9.B.4
Which of the following best identifies the purpose of matching the sign-up sheet against the cash box?
- A.It confirms the assistant is charging the correct session price.
- B.It is required by federal law for a business that accepts cash.
- C.It removes any possibility that the studio loses cash to theft.
- D.It is a cash-handling control that surfaces missing cash.
Check answerHide answer
Answer: D
- A.
- The near miss. A mismatched count could incidentally expose a mispriced session, but the control exists to surface missing cash, and the question asks for the purpose, not a side effect.
- B.
- No federal law prescribes this count. Cash-handling processes are internal mechanisms a business builds for itself, alongside codes of conduct and audit requirements, precisely because no outside rule covers a folding table of weekend cash.
- C.
- A control catches losses and deters them; it removes no possibility. Cash can still go missing at a folding table, and a count is how the studio would find out.
- D.
- Correct. Access to a business's cash creates the opening for embezzlement and misuse of funds, so businesses build internal mechanisms: codes of conduct, audit requirements, and cash-handling processes like this one. The count compares two independent records, the sign-up sheet and the cash box, so a gap surfaces on its own with no accusation required. The control only works when it runs every time, on everyone, trusted people included.
- Question 43.9.B.2
Under U.S. law, which of the following best describes a protection built for investors in publicly held corporations?
- A.Corporations must submit financial records yearly for an independent audit.
- B.A government accountant must approve each quarterly statement before release.
- C.Investors must personally verify a corporation's statements before buying shares.
- D.Accountants' professional ethics codes are enforced as federal law.
Check answerHide answer
Answer: A
- A.
- Correct. U.S. law requires publicly held corporations to submit their financial records every year for auditing by independent accounting firms, and financial market regulations are designed to ensure investors get accurate information and protection from fraud. The logic is a loan officer's problem at market scale: strangers hand money to businesses they will never visit, so the law sends in an outside reader.
- B.
- This overshoots the mechanism. The auditor is an independent accounting firm, and no government accountant approves statements before release.
- C.
- The law runs the opposite direction: because investors cannot personally verify a corporation's books, the audit requirement does the verifying for them. No purchase of shares requires the buyer's own inspection first.
- D.
- This promotes professional codes into legislation. The codes accountants and financial managers work under, honesty, integrity, transparency, objectivity, confidentiality, are maintained and enforced by professional organizations, while the annual audit is a legal requirement.
- Question 53.6.B.6, 3.9.A.1, 3.9.A.3
Lightwell Revenue Two Ways
Elise drafts the first-quarter revenue line both ways, and the table shows the numbers.
Line | Amount Prior-year first-quarter revenue | $16,000 Sessions shot and delivered this first quarter | $14,000 Retainer checks received in March for summer weddings | $6,000 Version one: sessions only | $14,000 Version two: sessions plus retainers | $20,000 Which conclusion is supported by the table?
- A.Version two shows the studio earned 20,000 dollars in the first quarter.
- B.Version one understates revenue, because the retainer checks had cleared.
- C.Version two turns a 12.5 percent revenue decline into a 25 percent increase.
- D.The studio's profit fell by 2,000 dollars from the prior-year quarter.
Check answerHide answer
Answer: C
- A.
- This reads the padded version as fact, and the table's own label defeats it: money for summer weddings is money the studio has not yet earned.
- B.
- Clearing the bank is not earning. Under the studio's own method, wedding revenue belongs to the quarter the wedding is shot, so the sessions-only version states the quarter correctly and understates nothing.
- C.
- Correct. Run the percent change equation twice from the same table. Version one: 14,000 against 16,000 is a change of minus 2,000, and minus 2,000 over 16,000 is minus 12.5 percent. Version two: 20,000 against 16,000 is plus 4,000, and 4,000 over 16,000 is plus 25 percent. The 6,000 dollars driving the swing is labeled in the table itself: retainers for summer weddings, payment for work that has not happened. One timing decision swings the story of the quarter by 37.5 points.
- D.
- This borrows a number the table never shows. Profit requires costs subtracted from revenue, this table carries no cost line, so no conclusion about profit is supported.
- Question 63.9.A.1
Which of the following best identifies an example of embezzlement?
- A.A restaurant owner reports half of the summer's cash sales to shrink the tax bill.
- B.A contractor pays a building inspector to pass wiring that failed inspection.
- C.A manager spends the office technology budget on a personal laptop for home.
- D.A bookkeeper entrusted with the accounts quietly moves sums into her own.
Check answerHide answer
Answer: D
- A.
- Tax evasion: portraying the business as smaller than it really is so the government collects less. Illegal, but misnamed as embezzlement.
- B.
- Paying an official to approve failed work is bribery: money offered to corrupt a decision. No entrusted funds are secretly taken; the wrong is the purchase of the inspector's signature.
- C.
- Misuse of funds, and the line between it and embezzlement is concealment inside entrusted money: the manager misdirected a budget in the open, while an embezzler secretly takes money she was trusted to manage.
- D.
- Correct. Embezzlement has three parts: money entrusted to someone's care, taken secretly, for personal gain, and the bookkeeper hits all three: trusted access, quiet transfers, her own account. The pattern hides inside authorized access, which is why it can run for years before anyone notices, and it is the crime that cash-handling controls and audit requirements exist to surface.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →7 Common Mistakes on 3.9
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
3.9.A.1 · 3.9.A.2 · 3.9.A.3 · 3.9.B.1 · 3.9.B.2 · 3.9.B.3 · 3.9.B.4