3.2 Borrowing, Credit, and Debt
Why consumers borrow, how lenders judge creditworthiness, and strategies to manage debt.
Part 1 of 4 Why People Borrow
Consumers borrow when what they want costs more than current income plus savings: a car, a house, tuition. Consumers also borrow to cover an emergency, to keep savings intact while buying, or because credit is convenient. Every kind of borrowing creates a debt for the borrower, and most borrowing charges interest.
What that interest costs depends on the lender, the type of loan, the amount, and the borrower's credit history. One distinction sorts every loan. A secured loan is backed by collateral that the lender can take. An unsecured loan is backed only by the borrower's promise.
| Lender | What to know |
|---|---|
| Commercial banks and credit unions | They lend the deposits placed with them by savers, businesses and other entities, to consumers and to businesses, nonprofits and governments |
| Mortgage and auto lenders | Property secures the loan, so rates are typically lower |
| Credit card companies and retail store cards | Unsecured, so priced for the risk |
| Alternative financial services | Payday loans, check cashing, instant tax refunds; lenders willing to take higher-risk borrowers typically charge higher rates |
Consumer protection laws require lenders to state credit terms clearly before any commitment, govern how debts may be collected, and forbid discriminatory lending. The published credit terms help only a borrower who reads them.
Part 2 of 4 What the Same Purchase Costs
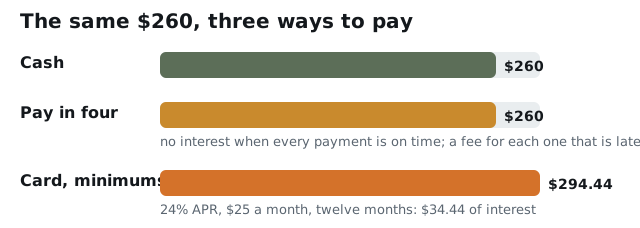
A 24% APR is 2% a month. A $260 balance repaid at $25 a month takes twelve months and costs $294.44. The $25 is the card's minimum payment. The same card charges no interest when the buyer has the cash first. Save the money before buying. Make the purchase with the card. Pay the full statement balance from the saved money. The repayment then appears in the buyer's credit history as an on-time payment.
Part 3 of 4 How a Lender Judges You
Every lender faces default risk, the chance a borrower never repays, so it prefers low existing debt, solid income and savings, and a record of on-time payments. Lenders who accept riskier applicants charge more. To decide whether to lend, a lender collects information about the applicant's income, savings and existing debt, and gets the applicant's credit report. A credit report is the record of a person's past use of credit. Credit bureaus compile each credit report from every interaction with a financial institution, such as an account opened, a loan taken, a card applied for or a payment made.
The report carries a credit score and can be shared with lenders, employers, landlords, insurers and government agencies. Income and savings count, and so does the record of repayment. A credit report with no borrowing on it has no repayment record. A first on-time payment starts the repayment record.
Part 4 of 4 Managing Credit and Debt
High debt harms a household because loan payments consume income that could be saved or spent, and bigger balances or higher rates push the payment up. Borrowers have trouble repaying debt when income drops or when loan payments grow larger than the borrowers can pay.
| Move | Why it works |
|---|---|
| Pay every bill on time | A score is built from payments that arrived when promised |
| Repay the highest-rate debt first | Card balances before anything cheaper |
| Keep card balances low and few, well under the credit limit | Using a small share of the credit limit raises the score |
| Compare lenders before borrowing | Comparing terms finds lower rates and lower fees |
| Make a down payment on a home or car | Paying part from savings shrinks the loan and every payment after it |
A borrower whose debt has become unmanageable, and whose property may be seized, can get debt management assistance. Bankruptcy is the legal process that eliminates some debts and sets up a repayment plan for the rest. The costs of bankruptcy persist for years.
A $260 card purchase costs $260 when the buyer pays the statement in full from saved cash. The same purchase costs $294.44 when the buyer pays only the minimum.
Worked Examples
The true cost of a $260 balance at 24% APR
Compute the total repaid and the interest paid when a balance is carried at a stated APR and a fixed monthly payment.
A student card offers 24% APR. Putting a $260 pass on it and paying $25 a month, work out how long the debt lasts and what it costs in total.
- Balance charged
- $260
- Annual percentage rate
- 24%
- Monthly payment
- $25
1. Convert the APR into a monthly rate
Card interest is applied monthly, so divide the annual rate by twelve. 24% over 12 months is 2% a month.
2. Write the rule for one month
Each month the balance grows by 2% and then the payment is subtracted. In month one, $260 times 1.02 is $265.20, and $265.20 minus $25 leaves $240.20.
3. Repeat until the balance clears
Applying the same rule month after month, the balance falls below $25 during the twelfth month, so eleven full payments of $25 are made and the final payment is $19.44.
4. Add up everything paid
Eleven payments of $25 is $275, and adding the final $19.44 gives $294.44.
5. Separate the interest from the debt
Subtract the amount originally borrowed. $294.44 minus $260 is $34.44 of interest.
Check answerHide answer
Answer
$294.44 in total, $34.44 of it interest. Carrying the balance stretches a single purchase across a year and adds $34.44 to its price.
Why it matters
Notice what the $34.44 actually bought: about two weeks of not waiting. Stating the cost of borrowing as a total rather than a rate is what makes that trade visible.
Pay-in-four: the price holds, the schedule moves
Show that an interest-free installment plan changes the timing of a cost rather than its size, and price the fee risk.
A pay-in-four checkout splits the $260 pass into four payments, the first taken at checkout and the other three every two weeks after it, with no interest if every payment lands on time and a $10 late fee for each one that does not. The third payment falls in the week the $90 travel share is due, and the fourth falls in the week the $100 of spending money is due.
- Purchase price
- $260
- Number of payments
- 4
- First payment
- taken at checkout
- Interval
- every 2 weeks
- Late fee per missed payment
- $10
1. Find the payment
Divide the price by the number of installments. $260 over 4 is $65.
2. Confirm the price is unchanged
Add the four payments back up. Four times $65 is $260, exactly the sticker price, so the plan itself adds nothing when it is paid perfectly.
3. Lay each payment date against that week's other obligations
With the first payment taken at checkout, the four land at weeks 0, 2, 4, and 6. Week 4 carries payment three of $65 plus the $90 travel share, so $155 comes due that week. Week 6 carries payment four of $65 plus the $100 of spending money, so $165 comes due that week.
4. Price the failure case
Missing both of the colliding payments costs two fees. Two times $10 is $20, so the $260 purchase becomes $280.
Check answerHide answer
Answer
$260 if perfect, $280 with two missed payments. The plan rearranges when money is owed and leaves the price alone, provided nothing slips.
Why it matters
A zero-interest plan is not a zero-risk plan. The cost hides in the calendar, so the honest way to evaluate one is to write the payment dates next to every other obligation already sitting in those weeks.
Rebuilding a savings balance after a planned purchase
Track a savings balance through a withdrawal and back up to the remaining obligations.
By week 7 the automated transfers have built the fund to $280, and the $260 pass is bought with cash already saved. Five weeks of saving remain before the festival, and $90 of travel share plus $100 of spending money are still to be paid.
- Balance at week 7
- $280
- Pass price
- $260
- Weeks of saving remaining
- 5
- Weekly transfer
- $40
- Travel share still owed
- $90
- Spending money still owed
- $100
1. Subtract the purchase
Take the pass out of the balance. $280 minus $260 leaves $20.
2. Add the remaining transfers
Five more Fridays at $40 each add $200. Adding that to the $20 remaining gives $220 by festival week.
3. Total the costs still to come
Add the two outstanding items. $90 plus $100 is $190.
4. Compare the balance against the obligations
Subtract what is owed from what is saved. $220 minus $190 leaves about $30.
Check answerHide answer
Answer
about $30 of slack. The fund reaches $220 against $190 of remaining costs, finishing roughly $30 ahead.
Why it matters
The cushion built into the original transfer is what absorbed an early purchase without breaking the plan. A savings plan with no slack has no room for the thing that always happens.
Key Terms
- Alternative Financial Services
- APR
- Bankruptcy
- Borrower
- Collateral
- Commercial Bank
- Credit
- Credit Bureaus
- Credit Card
- Credit Limit
- Credit Report
- Credit Score
- Credit Union
- Creditworthiness
- Debt
- Debt Management Assistance
- Debt-to-Income Ratio
- Default
- Delinquency
- Down Payment
- Installment Loan
- Interest
- Interest Rate
- Lender
- Loan
- Minimum Payment
- Principal
- Revolving Credit
- Secured Loan
- Unsecured Loan
Practice Questions
6 questions. Nothing here is recorded or scored.
- Question 13.2.A.2
Alina Voss
Alina Voss, eighteen, needs a car to reach her community college classes and her weekend job. The used car she wants costs 3,600 dollars, and her savings hold 900. She is comparing four ways to pay: financing arranged by the dealer, an auto loan from her credit union, a no-interest family loan from her cousin, and her own credit card, with a 2,000-dollar limit and a 26 percent APR. The credit union quotes a lower rate than the dealer but requires a down payment, and it asks for proof of income, her savings balance, and permission to pull her credit report.
Which of the following best explains why the credit-union auto loan would carry a lower interest rate than Alina's credit card?
- A.Credit unions are nonprofit, so state law caps the rate they charge on car loans.
- B.The car secures the auto loan, so the lender can recover the vehicle on default.
- C.Auto loans are priced by the vehicle's age, so a used car earns a lower rate.
- D.The card's 26 percent rate is high because its 2,000-dollar limit is small.
Check answerHide answer
Answer: B
- A.
- The invented law. Credit unions often do charge less, but no law sets their rates; the collateral does the work here.
- B.
- Correct. Borrowing creates a liability repaid with interest, and the interest rate prices the lender's risk. A loan that buys an asset able to serve as collateral, a car or a house, is a secured loan: if the borrower defaults, the lender takes the collateral and recovers much of its money, so lower risk prices as a lower rate. The card is unsecured, backed only by Alina's promise, so it charges more.
- C.
- Lenders do look at what an asset is worth when they size a secured loan, but the gap the question asks about runs between a secured loan and an unsecured card. Collateral prices that gap; the car's model year does not.
- D.
- The card's rate is high because the debt is unsecured, not because the limit is small. A credit limit sizes how much can be borrowed; the rate prices the lender's risk of not being repaid.
- Question 23.2.B.1, 3.2.B.2
Which of the following best describes the purpose of the credit union's requests for proof of income, her savings balance, and her credit report?
- A.A legal formality the state imposes on borrowers under twenty-one who finance a car.
- B.A signal that the credit union would rather not lend to a first-time borrower.
- C.A confirmation of the used car's resale value, since that car will secure the loan.
- D.An evaluation of Alina's creditworthiness, the lender's estimate of default risk.
Check answerHide answer
Answer: D
- A.
- No such formality exists in the framework, and the requests have nothing to do with Alina's age. Lenders ask every borrower for this file, because every borrower carries default risk the lender must price.
- B.
- The requests are how a lender says maybe, not no. Screening a first-time borrower is the standard path to approving one; a lender that preferred not to lend would simply decline.
- C.
- This stretches the collateral logic too far. The car's value matters to a secured loan, but every item on this list is about Alina, because the lender prices the borrower whether or not collateral exists.
- D.
- Correct. Every lender faces default risk, the chance that a borrower never repays, so lenders size up each borrower before naming a rate. The file is exactly what the credit union asked for: income, savings, existing debt, and a credit report of her past use of credit, compiled by a credit bureau. A strong file earns approval and a better rate; a risky file earns a higher rate or a no.
- Question 33.2.A.5
The dealer's financing paperwork includes a boxed section stating the loan's annual percentage rate, all fees, and the total amount Alina would repay. Which of the following best explains why that box appears?
- A.Consumer protection laws require lenders to state credit terms clearly to borrowers.
- B.Dealers add the box voluntarily, because clear terms attract more borrowers than fine print.
- C.Credit bureaus require the box before they will add the loan to a borrower's credit report.
- D.Disclosure boxes are required only on secured loans larger than 5,000 dollars.
Check answerHide answer
Answer: A
- A.
- Correct. Consumer protection laws require lenders to state credit terms clearly and explicitly before a borrower commits; the same body of law governs debt collection tactics and prohibits discriminatory lending. The box is where a borrower computes the true cost in advance, which is what lets Alina compare the dealer against the credit union.
- B.
- This turns a legal requirement into a courtesy. Disclosure does not depend on the dealer's goodwill.
- C.
- This misplaces the credit bureau, which records credit use and writes no loan contracts.
- D.
- The disclosure requirement is not limited by loan size or by whether collateral backs the loan. Consumer protection law requires clear statement of credit terms to borrowers generally, and this loan would qualify either way.
- Question 43.2.C.4
A twenty-year-old with a low credit score wants to raise it over the next two years. Which of the following strategies best supports that goal?
- A.Opening several new credit cards at once to show lenders more available credit.
- B.Carrying a balance on one card each month so the lender earns steady interest.
- C.Paying bills on time, paying down debt, and minimizing credit card use.
- D.Switching banks so that her old credit report stops following the new accounts.
Check answerHide answer
Answer: C
- A.
- Opening several new cards adds available credit but works against the goal: a score reflects past use of credit, and a burst of new accounts adds no history of on-time payment while inviting more debt. More open credit is not the same as a better record.
- B.
- The most widespread credit myth. The report records whether payments arrive on time, and interest paid buys no extra history; a balance paid in full on time builds the same record at zero cost.
- C.
- Correct. A credit score reflects past use of credit, so the score rises when the record improves, and the framework names three moves: pay bills on time, pay off existing debt, and minimize credit card use. A score is built from years of small, clean entries.
- D.
- This misunderstands the report. Bureaus compile it from her activity at every financial institution, so the file follows the consumer, whichever bank she uses.
- Question 53.2.A.2, 3.2.C.5
Alina's Loan Comparison
The table prices Alina's four options for paying for the 3,600-dollar car.
Option | Down payment | Repayment | Total repaid after down payment | Notes Dealer financing | None | 36 payments of $122 | $4,392 | Credit-union loan | $360 | 36 payments of $101 | $3,636 | Family loan | None | 24 payments of $150 | $3,600 | Never reported to a credit bureau Credit card | None | 26% APR | | $2,000 limit, below the car's price Which conclusion is supported by the table?
- A.Dealer financing is the cheapest path because it asks for no cash up front.
- B.The family loan is the strongest choice for building Alina's credit history.
- C.The dealer loan and the credit-union loan charge about the same total interest.
- D.The down payment and the lower rate halve the credit-union loan's interest cost.
Check answerHide answer
Answer: D
- A.
- This fails the supported-by-data rule. No cash up front is true, but cheapest is false: the dealer's all-in cost is 4,392 dollars against the credit union's 3,996.
- B.
- This contradicts the table's own line. A loan never reported to a credit bureau builds no credit history at any price.
- C.
- The two interest totals are nowhere near the same. The dealer collects 792 dollars of interest on the full 3,600 lent, while the credit union collects 396 on its smaller loan; one is exactly double the other.
- D.
- Correct. Compute both interest costs. The dealer lends the full 3,600 and collects 4,392: 792 dollars of interest. The credit union lends 3,240, the price minus the down payment, and collects 3,636: 396 dollars of interest, exactly half. Comparing lenders found the lower rate, and the down payment shrank the loan, so every payment after it shrank too.
- Question 63.2.A.4, 3.2.B.1
A borrower needs 300 dollars for two weeks, until the next paycheck arrives. Which of the following best identifies the most expensive source for that money?
- A.A personal loan from the borrower's credit union.
- B.A payday loan taken at a storefront lender.
- C.An auto loan secured by the borrower's own car.
- D.A credit card charge paid off at the statement.
Check answerHide answer
Answer: B
- A.
- The other end of the lineup. Banks and credit unions lend out the deposits savers place with them and screen borrowers carefully, usually the cheapest source and the hardest yes.
- B.
- Correct. Payday loans, check-cashing services, and instant tax refunds are alternative financial services, the most expensive lending in the market, because they serve the borrowers other lenders turn away, and the more default risk a lender absorbs, the more it charges. Two weeks of payday fees, restated as an annual rate, can dwarf even a high card APR.
- C.
- A secured loan sits near the cheap end of the lineup, because the collateral lowers the lender's risk. It is also the wrong tool for a two-week gap, but on price alone it cannot be the most expensive source here.
- D.
- This looks expensive because card APRs run high, but the mechanism decides: a charge paid off at the statement accrues no interest at all, making it the cheapest borrowing on this list.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →7 Common Mistakes on 3.2
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
3.2.A.1 · 3.2.A.2 · 3.2.A.3 · 3.2.A.4 · 3.2.A.5 · 3.2.B.1 · 3.2.B.2 · 3.2.B.3 · 3.2.B.4 · 3.2.C.1 · 3.2.C.2 · 3.2.C.3 · 3.2.C.4 · 3.2.C.5 · 3.2.C.6