3.1 Saving for Future Purchases
Why consumers save, the barriers to saving, and how to build a savings plan.
Part 1 of 4 Why People Save
Most consumers earn income by working for a business, a nonprofit or a government, and some add income from self-employment, rent, government programs, investments or retirement accounts. What is left after spending is the only money that can be saved.
| Reason | Example | How far away |
|---|---|---|
| A significant future purchase | A car, a home, college tuition, or a $450 festival weekend in May | Weeks to years |
| An emergency | A lost job, an illness | Unknown |
| Retirement | Income after the paychecks stop | Decades |
Saving for retirement, a long-term goal, works the same way as saving for a short-term goal such as the festival weekend, with a far longer deadline. The deadline decides which savings vehicle fits the goal.
Every dollar saved becomes a personal asset and may earn interest, which can be income now or later. How much depends on the interest rate, the amount saved, the vehicle that holds it, and conditions in the economy. $40 a week for twelve weeks at 4% earns about two dollars. With a balance that small, the savings account's main use is to keep the saved money separate from spending money. The interest rate matters only when the balance grows and the time frame gets longer.
Part 2 of 4 What Makes Saving Hard
| Group | Barrier | Why it blocks saving |
|---|---|---|
| Money | Inconsistent income | A fixed weekly transfer needs a fixed weekly paycheck |
| Money | Recurring expenses above income | Expenses use up all the income, so no money is left to move to savings |
| Psychological | Instant gratification | A person chooses a smaller reward tonight over a larger reward in twelve weeks |
| Psychological | Impulse buying | The unplanned purchase; stores are designed to produce it |
| Psychological | Lifestyle inflation | Spending climbs to match every raise, and the savings rate never moves |
Two kinds of program work against those barriers. An automated savings plan moves a set amount to savings every pay period before the money is seen. Retirement savings plans and health savings accounts cut taxes on money set aside for those purposes. With an automated savings plan, the saver decides once.
Consumers decide how much to save from their goals and their current income and expenses. A $450 goal in twelve weeks is $37.50 a week, rounded up to $40 for a margin of safety. The $40 is about 29% of $140 of weekly net pay. The rest of that weekly pay still covers the saver's expenses.
Consumers with defined goals and fewer barriers save more. The example goal is $450 in twelve weeks, saved at $40 a week.
Part 3 of 4 Outside Forces on a Savings Plan
| Factor | What it does to saving |
|---|---|
| Economic | A weak economy costs income; a strong one raises the cost of living. Either way, less is left after the necessary expenses |
| Economic | Inflation reduces the purchasing power of money already saved: the price of a $240 ticket that now costs $260 rose about 8%. Expected inflation can discourage saving outright |
| Political | Tax policy rewards saving: income placed in designated retirement, health care or childcare accounts can escape some income tax |
| Legal | Regulators oversee commercial banks and credit unions for consumer protection and stability; federal insurance covers each depositor up to $250,000 per bank |
Part 4 of 4 Choosing a Savings Vehicle
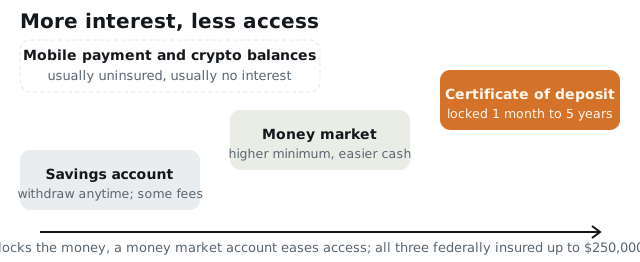
Consumers pick a vehicle by how much they are saving, the goal, the time frame, outside forces, and each option's benefits and costs. Four of an option's benefits and costs belong to the account: the interest rate, fees, the minimum deposit and risk. Three belong to the institution: location, convenience, reputation.
| Vehicle | Insured | What it offers | The cost or limit |
|---|---|---|---|
| Savings account | Yes | Interest, withdraw anytime | Some charge monthly fees; minimums and rates differ by institution |
| Money market account | Yes | Higher interest, easier access to cash | Larger minimum deposit, higher fees |
| Certificate of deposit | Yes | Typically the highest rate of the three, no monthly fee | Money locked for one month to five years; larger minimum |
| Mobile payment account | Usually not | One tap to spend | Typically no interest; no barrier against spending |
| Cryptocurrency account | Usually not | A hope that the asset gains value | No interest; value on the deadline is a guess |
Worked Examples
Sizing the weekly transfer from a goal and a deadline
Convert a dollar goal and a deadline into a weekly savings transfer and check it against take-home pay.
Sadie wants $450 for the Sunfall festival package by the end of May, twelve weeks away. She takes home about $140 a week from Hillcrest Market. Work out the automated transfer she should set, then test whether her paycheck can carry it.
- Savings goal
- $450
- Weeks available
- 12
- Weekly take-home pay
- $140
1. Divide the goal by the weeks available
Twelve equal deposits have to add up to $450, so start with the plain division. $450 over 12 weeks is $37.50 a week.
2. Round up to a figure a bank transfer can hold
A transfer of $37.50 is awkward and leaves zero room for a bad week, so round up to $40. Twelve deposits of $40 come to $480.
3. Measure the cushion the rounding buys
Subtract the goal from the plan. $480 saved against $450 needed leaves $30 of slack.
4. Test the transfer against weekly income
A plan she cannot sustain is not a plan. Divide $40 by the $140 she nets each week: 0.2857, or about 29% of take-home pay.
Check answerHide answer
Answer
$40 a week. Forty dollars every Friday for twelve weeks reaches $480 against a $450 goal, with $30 to spare, and consumes about 29% of weekly take-home pay.
Why it matters
The division is the easy half. The step that decides whether a savings plan survives is the last one, where the required transfer is checked against income that already has other jobs to do.
What 4.0% APY actually adds to a small balance
Estimate the interest a short savings plan earns and judge whether the rate is the reason to open the account.
Her account pays 4.0% APY. The balance starts at zero and climbs by $40 a week, and the week-7 withdrawal pulls it back down, so it averages about $130 across the twelve weeks. Estimate the interest earned.
- Annual percentage yield
- 4.0%
- Average balance over the period
- about $130
- Length of the period
- 12 weeks
1. Turn the annual rate into a rate for this period
Twelve weeks is 12 over 52 of a year, which is 0.2308 of a year. Multiply 4.0% by 0.2308 and the period rate is about 0.92%.
2. Apply the period rate to the average balance
Interest is earned on whatever is sitting there, so use the average rather than the ending balance. $130 times 0.0092 is about $1.20.
3. Compare the interest against the goal
Put $1.20 beside the $450 target. The interest covers about a quarter of one percent of the goal.
Check answerHide answer
Answer
a little over a dollar. Twelve weeks at 4.0% APY on an average balance near $130 earns a little over a dollar.
Why it matters
At this size the account is not chosen for its yield. It is chosen because it keeps the money one step away from being spent, and because the deposit is federally insured. Yield becomes the deciding factor only when balances and horizons both grow.
Measuring inflation on a single price
Compute the percentage increase in a price and state what it did to the purchasing power of money already saved.
Last year the same festival pass cost $240. This year it is listed at $260. Measure the increase, then say what it means for someone who had been saving toward the old price.
- Last year price
- $240
- This year price
- $260
1. Find the change in dollars
Subtract the earlier price from the current one. $260 minus $240 is $20.
2. Divide by the price it started from
Percent change always divides by the initial value, not the new one. $20 over $240 is 0.0833.
3. State it as a percentage
Multiply by 100. The pass rose about 8.3% in a year.
Check answerHide answer
Answer
about 8.3%. The price rose $20, an increase of roughly 8.3%, so a saver who targeted last year's number arrives $20 short of this year's.
Why it matters
This is purchasing power made concrete. The dollars saved did not shrink; what they can buy did. Over a long horizon that erosion is the argument for a savings vehicle that at least pays something.
Key Terms
- APY
- Automated Savings Plan
- Certificate of Deposit (CD)
- Checking Account
- Commercial Bank
- Compound Interest
- Cost of Living
- Credit Union
- Cryptocurrency
- Economy
- Emergency Fund
- Financial Goal
- Impulse Buying
- Income
- Inflation
- Instant Gratification
- Interest
- Interest Rate
- Lifestyle Inflation
- Liquidity
- Long-Term Goal
- Mobile Payment Account
- Money Market Account (MMA)
- Opportunity Cost
- Principal
- Purchasing Power
- Saving
- Savings Account
- Short-Term Goal
- Simple Interest
Practice Questions
6 questions. Nothing here is recorded or scored.
- Question 13.1.A.2
Devon Brooks
Devon Brooks, seventeen, runs a small lawn-mowing operation each summer and busses tables at a diner through the winter. Summer weeks bring in about 220 dollars; winter weeks bring in about 90, and some bring nothing when the diner cuts shifts. He is saving toward a 900-dollar laptop he will need for college in eight months, and the money sits in a payment-app balance on his phone. Last summer, when the mowing money was strong, he upgraded his phone plan and started buying lunch out most days, and by September the laptop fund had barely grown. His aunt suggests two changes: move the fund into an account at her credit union, and set an automatic transfer that moves a fixed amount on every payday.
Devon's laptop fund is best described as an example of which of the following reasons consumers save?
- A.Preparing for emergencies such as a lost job or illness.
- B.Building a source of income for the years after work ends.
- C.Saving for a significant planned future purchase.
- D.Earning interest as a source of current income.
Check answerHide answer
Answer: C
- A.
- The paired-concept swap. An emergency fund covers the events nobody schedules, a lost job or an illness, and a purchase with a known price and a known date is a goal, not an emergency.
- B.
- Retirement saving builds income for the years after work ends, decades away for a seventeen-year-old. Devon's target is a specific purchase eight months out, not a future income stream.
- C.
- Correct. The framework names three reasons consumers save: significant future purchases, future emergencies, and retirement income. A laptop for college is the significant-purchase reason wearing student clothes: it has a price, 900 dollars, and a date, eight months out.
- D.
- This confuses a side effect with a reason. Savings can earn interest, and interest on a fund this size comes to less than the price of the laptop's charger; nobody mows lawns all summer for it.
- Question 23.1.A.5
Devon's phone-plan upgrade and daily lunches after the strong mowing weeks best identify which barrier to saving?
- A.Lifestyle inflation, because his spending rose to match his summer income.
- B.Impulse buying, because each lunch was an unplanned purchase of the moment.
- C.Inconsistent income, because his mowing money arrives only in the summer.
- D.Inflation, because prices across the economy rose faster than his income.
Check answerHide answer
Answer: A
- A.
- Correct. Lifestyle inflation is spending that climbs to match a rise in income, and Devon's timeline matches it exactly: income jumped in June, a pricier phone plan and a lunch habit followed, and by September the fund had barely grown. Both new costs recur, resetting his baseline spending rather than emptying his pocket once.
- B.
- Impulse buying is the unplanned grab in the moment, one purchase at a time. A monthly phone contract plus a most-days lunch routine is a pattern that tracks his income, not a momentary lapse.
- C.
- Devon's income really is uneven across the year, but the fund stalled during the strong summer weeks, when money was arriving steadily. The barrier on display is what his spending did with that income, not the income's timing.
- D.
- The vocabulary borrow. Inflation is an economy-wide rise in prices, an outside economic factor, and nothing in the scenario says prices rose. Devon's spending rose.
- Question 33.1.C.7
Which of the following best explains the aunt's advice to move the laptop fund out of the payment app?
- A.Payment apps charge higher monthly fees than credit union savings accounts.
- B.App balances lose purchasing power to inflation while insured deposits do not.
- C.A credit union account would make the money easier to spend on short notice.
- D.The app balance typically earns no interest and carries no federal insurance.
Check answerHide answer
Answer: D
- A.
- The scenario gives no fee schedule for either the app or the credit union, so no fee comparison can support the advice. The real gap is interest and insurance, not monthly charges.
- B.
- This hands inflation a power it does not have: inflation shrinks what a dollar buys wherever that dollar sits, insured or uninsured, so it cannot separate these two vehicles.
- C.
- This reverses the benefit. Easy spending is the app's flaw, and the useful friction runs the other way: a savings account puts a small barrier between Devon and his own money.
- D.
- Correct. A payment-app balance is a storage spot rather than a savings vehicle: unless it is offered through an insured financial institution, no federal insurance protects it, and it typically pays no interest. A savings account at the credit union pays interest, is insured by the federal government up to 250,000 dollars, and puts a small barrier between Devon and his own money.
- Question 43.1.A.4
A hospital lets employees route part of each paycheck, before income tax is calculated, into an account reserved for medical expenses. Which of the following best identifies this saving incentive?
- A.An automated savings plan, because a set amount moves out each pay period.
- B.A health savings account, because the tax break follows money set aside for health costs.
- C.A certificate of deposit, because the money is reserved for a single purpose.
- D.Federal deposit insurance, because the account shields the employees' deposits.
Check answerHide answer
Answer: B
- A.
- A strong trap, because the money really does move on each payday. Automation is how the plan runs, but the incentive the stem describes is the tax break, which an ordinary automated transfer into a plain savings account never earns.
- B.
- Correct. The framework names three programs that incentivize saving: automated savings plans, which move a set amount of income each pay period; retirement savings plans, which cut taxes on money saved for retirement; and health savings accounts, which cut taxes on money set aside for health expenses. The defining feature here is income escaping tax because it goes to medical costs, so this is the health savings account exactly.
- C.
- A certificate of deposit locks money away for a set term in exchange for a higher rate; it carries no tax advantage and has no connection to medical expenses. Being reserved for one purpose is the employee's designation, not what a CD does.
- D.
- This names a protection rather than an incentive. Insurance keeps deposits safe whether or not a consumer ever saves another dollar; it does not reward the act of saving.
- Question 53.1.C.2, 3.1.C.3
Devon's Savings Options
Devon has 600 dollars saved and needs the laptop money ready in eight months. His aunt's credit union lists four options, and the table shows them.
Option | Annual yield | Minimum | Terms Savings account | 3.8% | $25 to open | No monthly fee Money market account | 4.3% | $2,500 minimum balance | Six-month CD | 4.5% | $1,000 | No withdrawals for six months Twelve-month CD | 4.9% | $1,000 | No withdrawals for twelve months Which conclusion is supported by the table?
- A.The savings account is open to Devon, because its minimum is 25 dollars.
- B.The twelve-month CD fits Devon's plan best because it pays the highest rate.
- C.The money market account is the riskiest option because it carries no federal insurance.
- D.The six-month CD frees Devon's money before his deadline, so the table supports opening one.
Check answerHide answer
Answer: A
- A.
- Correct. Read the minimum column first: the money market wants 2,500 dollars, both CDs want 1,000, and Devon holds 600, so only the savings account with its 25-dollar minimum is open to him today. The honest arithmetic on yield: 600 dollars at 3.8 percent earns about 23 dollars in a year, roughly 15 by his deadline, so the automatic deposits will move this fund far more than any rate on the table.
- B.
- The highest-rate bait. 4.9 percent fails twice, on a 1,000-dollar minimum Devon cannot meet and on a twelve-month lock that runs four months past an eight-month deadline. Higher interest typically asks for something back, here both a bigger minimum and a longer lock.
- C.
- All four accounts at this insured credit union carry the same federal insurance, so insurance eliminates nothing on this card. The table gives no basis for calling any option uninsured.
- D.
- The half-supported conclusion. The six-month clock does end inside his eight months, but the same row's minimum column still reads 1,000 dollars, so the table blocks the account it seems to recommend. A supported conclusion has to survive every column.
- Question 63.1.B.2
Which of the following best explains how expected inflation affects a consumer's incentive to save?
- A.Inflation forces banks to raise savings-account rates in step with rising prices.
- B.Inflation raises the purchasing power of the money already held in savings.
- C.Inflation is a legal factor requiring the government to insure larger deposits.
- D.Inflation erodes purchasing power, so expecting it weakens the incentive to save.
Check answerHide answer
Answer: D
- A.
- Economic conditions do move interest rates, but nothing forces a rate to keep pace with prices, so plenty of accounts pay less than inflation takes.
- B.
- This runs the effect backward. Inflation erodes purchasing power; it never adds to it. A dollar saved today buys less, not more, after prices across the economy rise.
- C.
- This files inflation in the wrong drawer. Inflation is an economic factor, and deposit insurance and bank regulation are the legal factors, a swap exam writers like to offer.
- D.
- Correct. Inflation is an increase in the prices of goods and services across an economy, and it erodes the purchasing power of savings: a dollar put away today buys fewer goods when it comes back out. If a 900-dollar laptop costs 5 percent more next year, the price becomes 945 dollars, and money saved toward the old price arrives 45 dollars short. A consumer who expects that erosion has a real reason to spend now rather than save.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →8 Common Mistakes on 3.1
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
3.1.A.1 · 3.1.A.2 · 3.1.A.3 · 3.1.A.4 · 3.1.A.5 · 3.1.B.1 · 3.1.B.2 · 3.1.B.3 · 3.1.B.4 · 3.1.C.1 · 3.1.C.2 · 3.1.C.3 · 3.1.C.4 · 3.1.C.5 · 3.1.C.6 · 3.1.C.7