3.6 The Income Statement
The components of an income statement and how to use one to evaluate performance.
Part 1 of 4 What an Income Statement Is
An income statement, also called a statement of profit and loss, compares a business's total revenue with its total costs over a period; the difference is net profit or loss. The statement usually prints several periods side by side, so every line can be judged against its own history.
Three categories hold almost every line: revenue, cost of goods sold and operating expenses. Interest, taxes and any nonrecurring expense take labeled lines of their own, so a reader knows a one-time repair will not return next month.
Part 2 of 4 Revenue to the Bottom Line
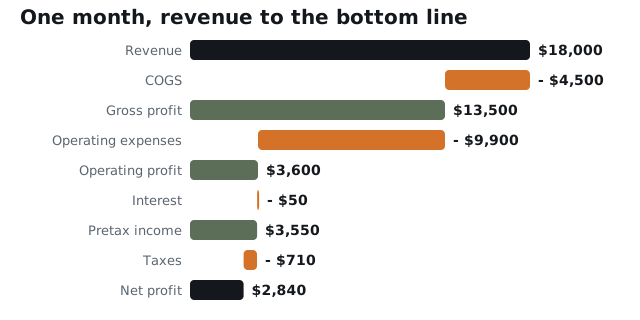
| Line | What it is | This month |
|---|---|---|
| Revenue | Income from the core activities, such as sales | 3,000 drinks at $6.00: $18,000 |
| Cost of goods sold | The direct costs of what was sold | $1.50 a drink: $4,500 |
| Gross profit | Revenue minus COGS: profit after only the direct costs | $13,500 |
| Operating expenses | Selling expenses (advertising, sales pay) plus general and administrative (office pay, rent, insurance), plus research and development | $9,900 |
| Operating profit | Gross profit minus operating expenses: income before interest and taxes | $3,600 |
| Interest expense | The cost of borrowing through loans or bonds; only the interest part of a payment | $50 |
| Pretax income | Operating profit minus interest | $3,550 |
| Taxes | Owed when pretax income is positive | 20%: $710 |
| Net profit | Pretax income minus taxes: the bottom line, what the owners earned | $2,840 |
Part 3 of 4 Reading the Margins
| Margin | Formula | What it grades | This month |
|---|---|---|---|
| Gross profit margin | Gross profit divided by revenue | Pricing and control of direct costs | 75% |
| Operating profit margin | Operating profit divided by revenue | Marketing and selling, administration, control of operating expenses | 20% |
| Net profit margin | Net profit divided by revenue | Overall profitability: the share of each revenue dollar that reaches the owners | 15.8% |
No margin means anything on its own. Each is benchmarked against projections, past performance and competitors, and only that comparison says whether performance meets expectations. Internal and external stakeholders read the same income statement. An owner spots trends and decides what to fix. A lender reads the income statement to judge a loan application.
The percent change equation works on any line: income, a cost, a profit, a margin. Revenue in February was $10,800, against $12,000 in February of the year before. Revenue fell $1,200, and $1,200 divided by $12,000 is a 10% drop. The equation measures the drop. The explanation has to come from the business: three days of a street closure is a fact only the business can add.
Part 4 of 4 Planning Forward
Incomes and expenses move with needs and wants, competitive pressure and PESTEL forces, so businesses and consumers plan. A projected income statement fills the same page with estimates. A business estimates projected revenue from the planned pricing and market research into demand. The business estimates projected COGS and operating expenses from the production plan, the supply chain and the planned occupancy, marketing, salaries and research spending. A current income statement is built from tracked revenues, expenses and taxes. A projected peak month of 4,200 drinks at $6.00 is $25,200 of revenue and $6,300 of COGS, while the operating lines hold near $9,900.
The projection plans for expected costs, shows what funding is needed, and says how much cash must be on hand to meet obligations. A consumer's budget has the same layout as a projected income statement. Expected net pay for a month or a year goes at the top. Every planned saving and expense, including debt payments, goes beneath the net pay. The budget shows spending patterns and whether the household's goals, such as managing debt, saving ahead and giving to causes, are being met.
A budget for a month with $560 of net pay sets aside $160 for saving, $40 for a phone, $60 for transport, $120 for food and fun, $40 for gifts and $20 to repay a family loan. The other $120 stays unassigned. That budget is a personal income statement, line for line.
Worked Examples
Building an income statement from revenue to net profit
Work an income statement top to bottom and arrive at the bottom line.
A shop sold 3,000 units this month at a $6.00 average. Ingredients and packaging cost $1.50 per unit. Operating expenses were $9,900, interest expense was $50, and the tax rate is 20%. Build the statement.
- Units sold
- 3,000
- Average price
- $6.00
- Variable cost per unit
- $1.50
- Operating expenses
- $9,900
- Interest expense
- $50
- Tax rate
- 20%
1. Compute revenue
Multiply units by price. 3,000 times $6.00 is $18,000, the top line.
2. Compute cost of goods sold
Multiply units by the direct cost each one carries. 3,000 times $1.50 is $4,500.
3. Subtract COGS to reach gross profit
$18,000 minus $4,500 is $13,500.
4. Subtract operating expenses to reach operating profit
$13,500 minus $9,900 is $3,600, which is income before interest and taxes.
5. Subtract interest expense to reach pretax income
Only the interest portion of a loan payment belongs here. $3,600 minus $50 is $3,550.
6. Apply the tax rate
Pretax income is positive, so tax is owed. 0.20 times $3,550 is $710.
7. Subtract tax to reach net profit
$3,550 minus $710 is $2,840.
Check answerHide answer
Answer
$2,840. The month produced $18,000 of revenue and $2,840 of net profit.
Why it matters
Each subtraction answers a different question, which is why the statement has stops rather than one calculation. An owner draw of about $2,000 then comes out of this $2,840 and never appears among the operating expenses above.
Converting three profit lines into three margins
Convert each profit line into a margin and state what each one grades.
Using the same month, with $18,000 of revenue, $13,500 of gross profit, $3,600 of operating profit, and $2,840 of net profit, compute the three margins.
- Revenue
- $18,000
- Gross profit
- $13,500
- Operating profit
- $3,600
- Net profit
- $2,840
1. Compute gross profit margin
Divide gross profit by revenue. $13,500 over $18,000 is 0.75, or 75%.
2. Compute operating profit margin
Divide operating profit by revenue. $3,600 over $18,000 is 0.20, or 20%.
3. Compute net profit margin
Divide net profit by revenue. $2,840 over $18,000 is 0.1578, or about 15.8%.
4. Read the cascade in cents
Each revenue dollar keeps 75 cents past direct costs, 20 cents past operating costs, and just under 16 cents once interest and tax are paid.
Check answerHide answer
Answer
75%, 20%, and 15.8%. The three margins fall from 75% to 20% to just under 16% as each layer of cost is removed.
Why it matters
A single margin proves nothing on its own. What makes these numbers usable is comparison, against the business's own projections, against its earlier months, and against businesses in the same line of work.
Running percent change on a revenue line
Compute the percentage change between two comparable periods and separate measurement from explanation.
February revenue came in at $10,800. The same month a year earlier produced $12,000. Compute the change, then decide what the number does and does not tell a reader.
- Current February revenue
- $10,800
- Prior February revenue
- $12,000
1. Find the change in dollars
Subtract the earlier figure from the current one. $10,800 minus $12,000 is negative $1,200.
2. Divide by the initial value
The denominator is always the period being compared against. Negative $1,200 over $12,000 is negative 0.10.
3. State it as a percentage
Multiply by 100. Revenue fell 10% year over year.
4. Separate the measure from the cause
The equation reports the size of the drop and says nothing about why. If three days of a street closure fell inside the month, only the business can supply that.
Check answerHide answer
Answer
negative 10%. Revenue fell $1,200, a decline of 10% against the same month last year.
Why it matters
A percent change is evidence, not a verdict. A reader handed the number without the explanation will grade the month wrong, which is why statements are read across several periods and why a filing that carries a footnote is worth more than one that does not.
Projecting a peak month before it arrives
Build the top of a projected income statement from a volume forecast and a held price.
Three years of history say July sells about 4,200 units. The price holds at $6.00 and the direct cost holds at $1.50. Project revenue, COGS, and gross profit for July, then state what the projection is for.
- Projected volume
- 4,200 units
- Planned price
- $6.00
- Direct cost per unit
- $1.50
1. Project revenue
Multiply the forecast volume by the planned price. 4,200 times $6.00 is $25,200.
2. Project cost of goods sold
Multiply the same volume by the direct cost. 4,200 times $1.50 is $6,300.
3. Project gross profit
Subtract the projected COGS from projected revenue. $25,200 minus $6,300 is $18,900.
4. Check the margin against the norm
Divide $18,900 by $25,200 to get 0.75. The gross margin holds at 75%, which is the sanity check that the projection was built consistently.
Check answerHide answer
Answer
$25,200 of revenue and $18,900 of gross profit. July projects to $25,200 of revenue, $6,300 of COGS, and $18,900 of gross profit at the usual 75% margin.
Why it matters
The projection earns its keep before July arrives. It shows the pre-buy of inventory that has to be funded, the extra shifts wages must cover, and how much cash needs to be standing by while the rush runs.
Key Terms
- Budget
- Cost of Goods Sold
- General and Administrative Expenses
- Gross Profit
- Gross Profit Margin
- Income Statement
- Interest Expense
- Loss
- Net Income
- Net Profit
- Net Profit Margin
- Operating Expense
- Operating Profit
- Operating Profit Margin
- Percentage Change Equation
- Pre-Tax Income
- Profit
- Projected Income Statement
- Revenue
- Selling Expenses
Practice Questions
6 questions. Nothing here is recorded or scored.
- Question 13.6.A.2, 3.6.A.5
Milpa Verde
Ines Vega owns Milpa Verde, a taco cart that works a downtown corner on weekday lunches. She buys tortillas, chicken, produce, and foil wrap from a restaurant supplier, rents overnight parking and prep space at a licensed commissary kitchen, pays one helper who takes orders and runs the register through the lunch rush, carries a liability insurance policy, and makes monthly payments on the loan that bought the cart. Each month she builds an income statement from register records and receipts and reads it beside last month's column before changing anything. This month, the organizer of a monthly food-truck rally offered her a paid Saturday spot for a flat vendor fee, and Ines is drafting next month's numbers with the rally included before she says yes.
On Milpa Verde's income statement, which of the following best describes how the cart's costs are organized?
- A.The ingredients, the foil wrap, the commissary rent, the wages, and the insurance are cost of goods sold.
- B.The ingredients and foil wrap are operating expenses, and the rent, wages, and insurance are cost of goods sold.
- C.The ingredients and foil wrap are cost of goods sold, and the rent, wages, and insurance are operating expenses.
- D.The ingredients, the foil wrap, and the helper's wages are cost of goods sold, and the rent and insurance are operating expenses.
Check answerHide answer
Answer: C
- A.
- This sweeps the whole cost list into one bucket. Necessary is a different test from direct: the rent, the wages, and the premium are every bit as necessary as the tortillas, and only the costs that become part of a taco are COGS.
- B.
- This runs the split exactly backward: it files the ingredients that go into each taco as overhead and the overhead as direct cost. The tortillas and foil leave the cart inside every order; the rent, wages, and insurance never do.
- C.
- Correct. An income statement sorts costs into cost of goods sold, the direct costs of producing what was sold, and operating expenses, the indirect costs of running the business around the product. Tortillas, chicken, produce, and the foil wrap go into each taco a customer buys, so they are COGS. The commissary rent, the helper's wages, and the insurance keep the business running whether any single taco sells or not, and statements typically split them further: the helper at the register is a selling expense, and the rent and insurance are general and administrative.
- D.
- The bait is the helper's paycheck. Wages sort by the job they pay for: Ines builds the tacos, the helper sells them at the register, and selling labor is an operating expense, not a direct cost of production.
- Question 23.6.B.2
Ines wants one measure of how successfully the cart is pricing its tacos and managing its ingredient and packaging costs. Which of the following best identifies that measure?
- A.The net profit margin.
- B.The operating profit margin.
- C.The revenue growth rate.
- D.The gross profit margin.
Check answerHide answer
Answer: D
- A.
- This sits at the bottom of the statement and grades overall profitability, the share of each revenue dollar that reaches the owner, with interest and taxes mixed in. Too many other decisions ride along for it to isolate pricing and ingredients.
- B.
- One stop too far down. Operating profit margin folds in the rent, the wages, and the marketing, so it grades selling and administration on top of the recipe.
- C.
- Revenue growth measures how much more the cart sold, not how profitably it sold it. A month of underpriced tacos can grow revenue while the margin on each taco shrinks.
- D.
- Correct. Gross profit margin is gross profit divided by total revenue, and because gross profit subtracts only the direct costs, the margin isolates exactly two decisions: the prices on the menu board and the cost of what goes into each taco. Any margin only becomes a judgment when it is benchmarked against the cart's projections, its past months, and other food vendors.
- Question 33.6.C.2, 3.6.C.3
Which of the following best explains why Ines drafts next month's numbers before accepting the rally spot?
- A.A projected income statement records the revenue and costs the rally has already produced.
- B.Estimating the added revenue and costs in advance shows whether the rally adds profit.
- C.A projected income statement guarantees the rally will be profitable before she commits.
- D.Drafting the numbers moves the vendor fee off the statement, since one-time costs are excluded.
Check answerHide answer
Answer: B
- A.
- This describes the ordinary income statement, built from current financial data about what already happened; a projection is built from predictions.
- B.
- Correct. A projected income statement predicts revenues, costs, and the resulting profit or loss for a coming period. Future revenue is estimated from planned prices and expected customer demand at the rally; future costs come from the production behind it: extra ingredients, extra helper hours, the vendor fee. The projection shows whether the rally is expected to add profit and how much cash must be ready before Saturday arrives.
- C.
- No projection guarantees anything; it is a forecast built from estimates. The value is in the comparison it allows before committing, not in any promise about how the Saturday actually goes.
- D.
- This misreads one-time costs. A nonrecurring expense appears on its own labeled line so a reader knows it will not repeat; drafting a projection moves nothing off the statement.
- Question 43.6.C.4
A part-time bookstore clerk writes out a monthly plan: expected net pay of 900 dollars, allocated as 350 for a rent share, 200 for food, 60 for a bus pass, 120 for savings, 90 for a student-loan payment, 30 for donations, and a 50-dollar buffer. Which of the following best describes the plan?
- A.A consumer budget allocating expected net pay across savings, expenses, and debt.
- B.A consumer budget with one error, because a loan payment is not a planned expense.
- C.An income statement, because it reports what the clerk earned and spent last month.
- D.An incomplete plan, because charitable donations belong outside a consumer budget.
Check answerHide answer
Answer: A
- A.
- Correct. A consumer budget starts from expected net pay, income after taxes and other deductions, and allocates every planned saving and expense for the period, and debt payments are on the required list. Line for line, a budget is a personal projected income statement, and comparing it afterward with the month that actually happened shows spending patterns and whether the goals are on track.
- B.
- This invents a rule the framework states in reverse. A consumer budget includes all planned expenses including debt payments, so the 90 dollars belongs exactly where it is.
- C.
- The plan-versus-record swap. An income statement reports a period that already happened, and every number in this plan is a prediction.
- D.
- No rule pushes donations outside a budget. A budget allocates expected net pay across whatever the clerk plans to do with it, and a giving line is a planned expense like any other.
- Question 53.6.B.4, 3.6.B.6
Milpa Verde Income Statement
Ines finishes this month's income statement, and the table shows it, along with one comparison figure from last month's column.
Line | Amount Revenue | $8,000 Cost of goods sold | $3,200 Gross profit | $4,800 Operating expenses | $3,200 Operating profit | $1,600 Interest expense | $100 Pretax income | $1,500 Taxes | $300 Net profit | $1,200 Net profit, last month | $1,000 Which conclusion is supported by the statement?
- A.The cart's gross profit margin for this month came to 40 percent of revenue.
- B.Revenue grew 20 percent from last month to this month's total.
- C.The cart's operating profit margin for this month came to 33 percent.
- D.Net profit grew 20 percent, and net profit margin is 15 percent.
Check answerHide answer
Answer: D
- A.
- 3,200 over 8,000 is 40 percent, but that is the COGS share of revenue, the complement of the answer. Gross profit margin divides gross profit by revenue: 4,800 over 8,000 is 60 percent.
- B.
- The table shows exactly one figure from last month, net profit, so a claim about revenue growth has nothing to stand on.
- C.
- This divides operating profit by gross profit to get 33 percent. Every margin divides by total revenue, and 1,600 over 8,000 is 20 percent.
- D.
- Correct. Run both halves. Percent change is current value minus initial value, divided by initial value, times 100: 1,200 minus 1,000 is 200, and 200 over 1,000 is 20 percent growth. Net profit margin is net profit over total revenue: 1,200 over 8,000 is 15 percent. Both check out.
- Question 63.6.A.7, 3.6.A.9
A pottery studio's annual income statement shows a positive operating profit and a net loss on the bottom line. Which of the following best explains the result?
- A.Cost of goods sold ran greater than the studio's revenue for the full year.
- B.Interest expense on the studio's loans exceeded its operating profit.
- C.Taxes turned a positive pretax income into a net loss for the year.
- D.Operating expenses ran greater than the studio's gross profit for the year.
Check answerHide answer
Answer: B
- A.
- This would make gross profit negative, and the cascade never recovers: operating profit would come out negative too, and the question says it is positive.
- B.
- Correct. The statement runs in a fixed order: gross profit, then operating profit, then interest expense, then pretax income, then taxes, then net profit. Interest, the cost of borrowing through loans and at corporate scale through bonds, is subtracted after operating profit. When interest is bigger than operating profit, pretax income goes negative, no income tax is owed on a loss, and the loss carries straight to the bottom line: a studio that runs well but borrowed heavily.
- C.
- The order kills it. Taxes are only charged when pretax income is positive, and a tax takes a share of that income, so it shrinks a profit and never flips one into a loss.
- D.
- This fails the same test: operating expenses greater than gross profit would make operating profit negative, and the question says it is positive.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →7 Common Mistakes on 3.6
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
3.6.A.1 · 3.6.A.2 · 3.6.A.3 · 3.6.A.4 · 3.6.A.5 · 3.6.A.6 · 3.6.A.7 · 3.6.A.8 · 3.6.A.9 · 3.6.B.1 · 3.6.B.2 · 3.6.B.3 · 3.6.B.4 · 3.6.B.5 · 3.6.B.6 · 3.6.C.1 · 3.6.C.2 · 3.6.C.3 · 3.6.C.4 · 3.6.C.5 · 3.6.D.1 · 3.6.D.2 · 3.6.D.3 · 3.6.D.4