5.1 Taxes, Net Income, and Budgeting
How to read a pay stub, the taxes individuals pay, and how to build a monthly budget on the money that actually lands in your account.
Part 1 of 4 What a Pay Stub Records
Unit 5 covers personal finance you will use for life. The AP exam covers Units 1 to 4. A pay stub records three parts in order: gross income, the deductions taken from gross income, and net income. Gross income is set by the compensation scheme: a salary split across pay periods, hours times a rate, or a contracted sum.
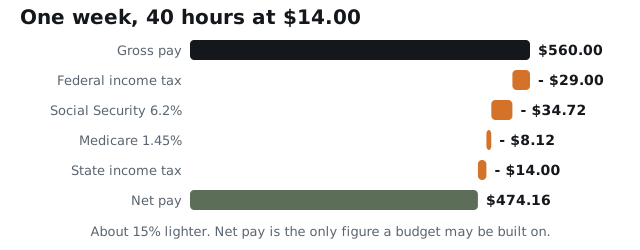
Mandatory deductions are required by law and withheld by the employer: income tax withholding and specific payroll taxes. Voluntary deductions are what the employee elects to route to employer-sponsored benefits: health insurance, health or dependent care savings, life insurance, retirement, union dues. Some voluntary deductions are pretax deductions, left out of taxable income, which lowers the tax bill and is a built-in reason to save. Net pay is the only figure a budget should be built on.
Part 2 of 4 The Taxes Individuals Pay
| Tax | Based on | How it gets paid |
|---|---|---|
| Income tax | A percentage of income | Withheld from each paycheck by the employer; the annual income tax return settles the rest or returns an overpayment; the self-employed pay it themselves |
| Payroll taxes | Wages, at set rates, to fund Social Security, Medicare, Medicaid and unemployment benefits | Withheld; for Social Security and Medicare the employer pays half, and the self-employed pay both halves as self-employment tax |
| Capital gains tax | The gain when an asset sells above what was paid | Filed with the income tax return, usually at a lower rate |
| Property tax | The value of houses, land and, in some states, cars | Billed annually, semi-annually or monthly |
| Sales tax | The sale price of an item | Collected by the business making the sale, which sends it on |
Income tax withholding is a prepayment. A summer job's withholding table treats $560 a week as $29,120 of yearly income. The worker's real income for the year comes from 21 spring weeks at $156, 12 summer weeks at $560 and 17 fall weeks at $252, which adds to $14,280. The $14,280 total is under the standard deduction. The $348 of federal income tax withheld over the summer (12 weeks at $29) therefore comes back as a refund when the return is filed. Payroll tax does not come back as a refund. Payroll tax earns the worker credits toward Social Security and Medicare.
Part 3 of 4 Why Households Pay Different Amounts
| Factor | What it does | Examples |
|---|---|---|
| Progressive rates | Higher incomes pay higher rates; the marginal rate on the last dollar climbs with income | The federal income tax and some state taxes |
| Deductions | Lower taxable income before any rate is applied | Mortgage interest, retirement contributions, charitable donations, state and local taxes paid, some medical expenses |
| Credits | Subtract straight from the tax owed | A child tax credit, a child or dependent care credit, an education credit, credits for specific purchases |
Income sets the rate. The rest of a household's circumstances decides which deductions and credits apply. A dollar of credit is worth more than a dollar of deduction, because a credit is subtracted from the tax itself and a deduction only lowers the income the rate is applied to.
Part 4 of 4 A Budget on Net Income
A budget starts from expected net pay and assigns every dollar to saving, spending, debt repayment or a deliberate buffer before the period begins. Four checks of $474.16 are $1,896.64, planned as an even $1,896. Needs are what living requires, and wants improve it. A fixed expense such as a phone share holds steady. A variable expense such as fuel moves with behavior. When money runs short, cut discretionary spending first. The savings rate is the share of net pay routed to saving. Automate the transfer to saving on payday. The emergency fund starts with money from the deliberate buffer.
Once a goal is reached, the money in the budget line that funded the goal is no longer needed. Assign that money to a new budget line on purpose.
Worked Examples
Gross to Net on One Weekly Stub
Compute net pay from an hourly wage and the four mandatory deduction lines.
A front-end clerk works a full-time summer week at a grocery store: 40 hours at $14.00 an hour, paid weekly. The state charges a flat 2.5 percent income tax, Social Security is withheld at 6.2 percent and Medicare at 1.45 percent, and the federal weekly withholding table takes $29.00 at this pay level. The role carries no benefits, so every voluntary deduction line reads zero. Find the net pay.
- Hours worked
- 40
- Hourly wage
- $14.00
- Social Security rate
- 6.2%
- Medicare rate
- 1.45%
- State income tax rate
- 2.5% flat
- Federal income tax withheld
- $29.00
- Voluntary deductions
- $0.00
1. Find gross pay for the period.
Hourly workers gross the wage multiplied by hours worked, so 40 times $14.00 is $560.00. Nothing has been removed yet.
2. Withhold Social Security at the statutory rate.
Social Security is 6.2 percent of gross pay: 0.062 times $560.00 is $34.72.
3. Withhold Medicare at the statutory rate.
Medicare is 1.45 percent of gross pay: 0.0145 times $560.00 is $8.12. Together with Social Security this is $42.84 of payroll tax, and the employer pays a matching $42.84 that never appears on the stub.
4. Withhold state income tax.
A flat 2.5 percent state rate takes 0.025 times $560.00, which is $14.00.
5. Add the mandatory deductions together.
Federal $29.00 plus Social Security $34.72 plus Medicare $8.12 plus state $14.00 totals $85.84. Voluntary deductions add nothing here because every benefit line is zero.
6. Subtract total deductions from gross pay.
$560.00 minus $85.84 leaves $474.16, which is the amount that reaches the bank account.
7. State the gap as a share of gross.
$85.84 divided by $560.00 is about 0.153, so roughly 15.3 percent of the check never arrives.
Check answerHide answer
Answer
$474.16. Net pay for the week is $474.16, from $560.00 of gross pay, with $85.84 withheld across four mandatory lines.
Why it matters
The order matters more than the arithmetic. Gross is set by the compensation scheme, mandatory deductions are removed by law before anyone chooses anything, and net is what is left. Every plan built on the $560 figure is overbuilt by about fifteen percent.
The Same Method on a Smaller Paycheck
Apply the gross-to-net method at a pay level below the federal withholding threshold.
Before the summer promotion, the same clerk worked 12 hours a week at $13.00 an hour. The payroll and state rates are unchanged, but this gross sits below the level at which the federal weekly table withholds anything, so the federal line is $0.00. Find net pay.
- Hours worked
- 12
- Hourly wage
- $13.00
- Social Security rate
- 6.2%
- Medicare rate
- 1.45%
- State income tax rate
- 2.5% flat
- Federal income tax withheld
- $0.00
1. Find gross pay.
12 hours at $13.00 an hour is $156.00.
2. Withhold Social Security.
0.062 times $156.00 is $9.672, which rounds to $9.67.
3. Withhold Medicare.
0.0145 times $156.00 is $2.262, which rounds to $2.26.
4. Withhold state income tax.
0.025 times $156.00 is exactly $3.90.
5. Subtract the deductions.
$156.00 minus $9.67 minus $2.26 minus $3.90, with no federal line to subtract, leaves $140.17.
Check answerHide answer
Answer
$140.17. Net pay is $140.17 on $156.00 of gross pay. About 10 percent is withheld here against about 15 percent at the higher wage.
Why it matters
The percentage withheld is not fixed. Payroll and flat state taxes take the same share at any income, but federal income tax withholding depends on how much is earned, and at low enough pay it is zero. That is why the same method has to be rerun whenever pay changes rather than scaled from an old stub.
Annualized Withholding Against the Real Year
Predict a refund by comparing tax withheld to tax actually owed for a full year.
The federal weekly table read the summer stub as though $560.00 arrived every week of the year. The real calendar year was 21 spring weeks at $156.00, 12 summer weeks at $560.00, 17 fall weeks at $252.00, and 2 unpaid weeks. The standard deduction that year is roughly $16,000. Work out the federal income tax owed and the refund.
- Weeks at $156.00
- 21
- Weeks at $560.00
- 12
- Weeks at $252.00
- 17
- Unpaid weeks
- 2
- Federal withheld per summer week
- $29.00
- Payroll tax withheld per summer week
- $42.84
- Standard deduction
- about $16,000
1. See what the withholding table assumed.
The table annualizes the current check: 52 weeks at $560.00 is $29,120, an income far above what the year will actually produce.
2. Add the real year's gross pay.
21 times $156.00 is $3,276. 12 times $560.00 is $6,720. 17 times $252.00 is $4,284. The two unpaid weeks contribute nothing.
3. Compare the year against the standard deduction.
Federal income tax applies only to income above the standard deduction. $14,280 is below roughly $16,000, so taxable income is zero and the federal income tax owed for the year is zero.
4. Total the federal tax already withheld.
The summer table took $29.00 on each of 12 checks, which is $348. The spring and fall checks were below the withholding threshold and took nothing.
5. Settle up on the return.
Tax withheld of $348 against tax owed of $0 is an overpayment, and filing the annual return returns the whole amount.
6. Check what does not come back.
Payroll tax is not income tax. 12 weeks at $42.84 is $514.08 of Social Security and Medicare, and none of it is refunded; it buys credits in those programs.
Check answerHide answer
Answer
$348. The refund is $348, and the $514.08 of payroll tax withheld over the same weeks stays paid.
Why it matters
Withholding is a prepayment based on an assumption about the whole year, and the return is the correction. A refund means too much was prepaid, which is worth understanding rather than celebrating, and it never includes payroll tax.
Balancing a Monthly Budget on Net Pay
Convert weekly net pay into a monthly plan and solve for the unallocated buffer.
Using a four-week month, convert net pay of $474.16 a week into a monthly planning figure, then balance a plan with these lines: car fund $1,200, household contribution $100, phone share $40, transport $60, food and fun $200, gifts $40, and a $20 repayment on a $100 advance from parents. How large is the buffer?
- Weekly net pay
- $474.16
- Pay periods planned
- 4
- Car fund
- $1,200
- Household contribution
- $100
- Phone share
- $40
- Transport
- $60
- Food and fun
- $200
- Gifts and other
- $40
- Debt repayment
- $20
1. Find the monthly planning figure.
Four weekly checks of $474.16 total $1,896.64.
2. Round the plan down, not up.
Planning on an even $1,896 leaves the 64 cents sitting in checking. Rounding up would plan money that never arrives.
3. Add every named line.
$1,200 plus $100 plus $40 plus $60 plus $200 plus $40 plus $20 is $1,660.
4. Solve for the buffer.
$1,896 minus $1,660 leaves $236 unassigned. A plan is balanced only when the lines and the buffer sum exactly to the planning figure.
5. Give the buffer a destination.
An unspent buffer swept into savings at month end becomes the start of an emergency fund. A buffer with no destination is simply unplanned spending.
Check answerHide answer
Answer
$236. The plan balances at $1,896 with a $236 buffer, and sweeping that buffer into savings turns slack into an emergency fund.
Why it matters
Every dollar of net pay should have a job before the month starts, including the dollars left over. Naming the buffer and deciding in advance where it goes is what separates a budget from a guess, and it is why the debt repayment line stays visible until the debt is retired.
Key Terms
- Annual Income Tax Return
- Budget
- Capital Gains Tax
- Deduction
- Dependent
- Discretionary Spending
- Emergency Fund
- Fixed Expense
- Gross Income
- Income Tax
- Mandatory Deductions
- Marginal Tax Rate
- Needs
- Net Income
- Pay Stub
- Payroll Taxes
- Pre-Tax Deductions
- Progressive Tax
- Property Tax
- Sales Tax
- Savings Rate
- Self-Employment Tax
- Tax Credit
- Tax Deduction
- Tax Refund
- Taxable Income
- Taxes
- Variable Expense
- Voluntary Deductions
- Wants
- Withholding
Practice Questions
4 questions. Nothing here is recorded or scored.
Unit 5 is not assessed on the AP Business with Personal Finance Exam. The exam covers Units 1 through 4. Unit 5 supports the Financial Advisor Project and your own money decisions.
- Question 15.1.A.2, 5.1.A.4
Copperleaf Garden Center
Odette Quillen works part time at Copperleaf Garden Center, where her hours swing with the season: about 14 hours a week for most of the year and 34 hours a week through the ten-week spring planting rush, at $15.00 an hour. Her pay for the full year adds up to $13,920, which lands below the income level at which federal income tax begins, so the federal income tax she owes for the year works out to zero. Federal income tax still came out of her spring checks, $270 across the rush, because the payroll table reads each check as though the whole year paid at that week's rate. Social Security and Medicare come out of her checks year round. The owner has now offered Odette the lead grower job for next season at $19.00 an hour, and she is hesitating, because a friend told her that earning more can push a person into a higher tax bracket and leave her worse off.
Which of the following best describes what happens to the $270 of federal income tax withheld from Odette's spring checks?
- A.Copperleaf returns it in her last spring check, once her weekly hours drop back down.
- B.It stays with the government, because tax withheld from a paycheck settles the bill.
- C.Filing an annual return brings it back, since the withholding prepaid a bill of zero.
- D.It counts toward the Social Security and Medicare credits she is building, so it stays paid.
Check answerHide answer
Answer: C
- A.
- The employer is a collector, not a bank. Copperleaf sends what it withholds to the government on a set schedule, so by summer the $270 is already out of the garden center's hands, and the return Odette files is what brings it home.
- B.
- Treats a prepayment as a final bill. Withholding is an estimate paid in advance, and the actual bill is figured only once the year is finished and the return is filed. When the estimate runs above the bill, the difference comes back.
- C.
- Correct. Income taxes are a percentage of income paid to the government, and for an employee the employer withholds a portion of each paycheck and pays it in directly. The household then files an annual income tax return to pay whatever is still owed or to reclaim an overpayment. The payroll table read one $510 spring week as though the whole year ran at that pace, but Odette's real year came to $13,920, below where federal income tax begins, so the tax owed is zero and the $270 was an overpayment from the first dollar. Filing brings it back as a refund, which is money she loaned the government at no interest rather than a bonus for working the rush.
- D.
- Splits the difference between two lines on the stub. Social Security and Medicare are payroll taxes that fund those programs, and those dollars do stay paid and do build credits. The $270 line is federal income tax, a separate tax that gets settled on the return.
- Question 25.1.B.2, 5.1.B.1
Odette asks whether moving up to $19.00 an hour could leave her with less money after taxes than she keeps now. Which of the following is the best response?
- A.Yes, because a higher hourly rate moves her whole year of pay up to the higher rate.
- B.No, because the higher rate applies only to the income above the cutoff.
- C.No, because her federal income tax rate stays the same at any income she is likely to earn.
- D.Yes, because the payroll taxes withheld from her checks climb with her hourly rate.
Check answerHide answer
Answer: B
- A.
- This is the worry stated as a rule, and it is the part the friend got wrong. A progressive system does not go back and re-rate income that was already earned below the cutoff; the higher rate reaches forward to the dollars above it.
- B.
- Correct. The U.S. federal income tax is progressive, so higher incomes are charged higher rates, and the rate that climbs is the marginal rate, the rate on the last dollar earned. Raising Odette's pay from $15.00 to $19.00 an hour lifts her year above the level where the tax begins, and the new rate lands on the income above that line rather than on the income below it. She keeps less of each added dollar than she would have kept tax free, and she still ends up with more money than she has now. What the raise is worth turns on the job itself, not on a fear of the bracket.
- C.
- The right verdict for a reason the framework contradicts. Federal income tax rates do climb with income, and at $19.00 an hour Odette's year would rise past the point where the tax starts, so her rate is going to move. What holds steady is the rate charged on the income below the cutoff.
- D.
- The premise is accurate and the conclusion does not follow from it. Social Security and Medicare take a set percentage of pay, so a bigger check means a bigger payroll line and a bigger amount left after that line comes out.
- Question 35.1.A.6
A hardware store rings up a customer's purchase of $64.00 in goods, and the state charges a 6 percent sales tax on the sale. Which of the following conclusions is supported?
- A.The customer pays $67.84, and the store submits the $3.84 to the government.
- B.The customer pays $67.84, and the $3.84 is revenue the store earned on the sale.
- C.The customer pays $64.00, since the store owes the tax out of its own sales price.
- D.The customer pays $67.84, then reports the $3.84 later on a household tax return.
Check answerHide answer
Answer: A
- A.
- Correct. A sales tax is based on the sales price of an item, so 6 percent of $64.00 is $3.84 and the register total comes to $67.84. The business selling the item collects that tax and submits it to the government, which means the $3.84 passes through the store on its way somewhere else.
- B.
- Counts the tax as earnings. The store handles the $3.84 but owes it to the government, so it belongs in a tax payment rather than on the store's revenue line, and treating it as income leaves the store short when the payment comes due.
- C.
- Puts the tax on the wrong side of the counter. Sales tax is added to the sales price and paid by the buyer at checkout, and the seller's job is collecting that money and passing it along.
- D.
- Sends the payment to the wrong filer. An annual income tax return settles a household's income tax, while sales tax is submitted by the business that collected it, which is why the customer's part of this job ends at the register.
- Question 45.1.A.3
Two years ago a household bought shares in a fund for $3,000 and this year sold those shares for $4,200. The household also earned wages during the year. Which of the following best describes how the $1,200 gain is taxed?
- A.The gain is withheld from the household's paychecks during the year of the sale.
- B.The gain goes untaxed, since tax was already paid on the income used to buy the shares.
- C.The gain is taxed at the same rate as the household's wages for that year.
- D.The gain is reported with the annual return, usually at a lower rate than wages.
Check answerHide answer
Answer: D
- A.
- Withholding is an employer's job, and it covers pay. Nobody withholds tax from a sale of shares, so the gain reaches the government through the return the household files rather than through a paycheck.
- B.
- Taxes the wrong dollars. The $3,000 the household put in was taxed back when it was earned, and the tax here falls on the $1,200 the shares gained on top of that purchase price.
- C.
- Half of this holds up. The gain is reported on the same return as the wages, and that is where the similarity stops, because a capital gain is charged at its own rate rather than at the rate on ordinary income.
- D.
- Correct. A capital gain is what an asset earns above what was paid for it, here $4,200 minus $3,000, or $1,200. Capital gains taxes are submitted with the household's annual income tax return, and the rate charged on the gain is typically lower than the rate the same household pays on the income it works for.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →6 Common Mistakes on 5.1
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
5.1.A.1 · 5.1.A.2 · 5.1.A.3 · 5.1.A.4 · 5.1.A.5 · 5.1.A.6 · 5.1.B.1 · 5.1.B.2 · 5.1.B.3 · 5.1.B.4 · 5.1.C.1 · 5.1.C.2 · 5.1.C.3 · 5.1.C.4 · 5.1.C.5 · 5.1.C.6