5.2 Managing Personal Risk
Personal, property, and liability risk, how a policy and a premium work, how to choose coverage, and how to recognize fraud.
Part 1 of 4 Three Insurable Risks
Unit 5 covers personal finance you will use for life. The AP exam covers Units 1 to 4. Everyone carries financial and physical risk: a collision, an illness that stops work. Insurable risks involve a loss by chance that is quantifiable and statistically predictable, so an insurer can estimate the cost and the odds of the loss. That estimate lets an insurer quote a premium even for a teenage driver.
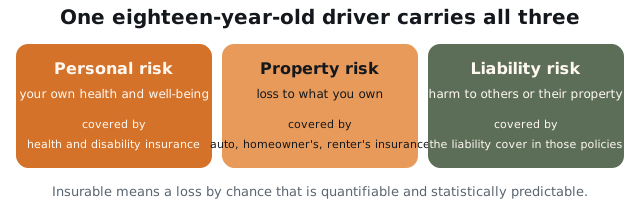
| Risk | Involves | For an eighteen-year-old driver |
|---|---|---|
| Personal risk | The health and well-being of the insured person | Injury in an accident; a serious illness |
| Property risk | Loss to property the insured person owns | A car dented, flooded or stolen |
| Liability risk | Harm to someone else or their property | A parked car scraped; a pedestrian struck by careless driving |
Part 2 of 4 How a Policy Works
Insurance trades a small scheduled payment for protection against a large unscheduled one. The buyer pays a premium (monthly, semi-annual or annual) for a policy with a chosen amount of coverage. When a covered loss occurs, the buyer files a claim for reimbursement. The buyer pays the deductible out of pocket before the insurer pays the rest. A higher deductible means a lower premium and more out-of-pocket cost for the buyer when a loss happens.
| Policy | What it pays for |
|---|---|
| Health insurance | Medically necessary care, and sometimes preventive care; often an employee benefit where the employer pays part or all of the premium |
| Auto, homeowner's and renter's insurance | Losses to the buyer's own property, and the legal liability for damage the buyer causes to other people or property |
| Life insurance | Funds to beneficiaries when the insured dies: replacing income, paying end-of-life costs, funding dependents' future needs |
| Disability insurance | Income when illness or injury stops a person working |
| Extended warranties and service contracts | Repair bills on an expensive car or appliance: a fee today against costs later, the same structure as a premium |
Part 3 of 4 Choosing Coverage
How much to buy depends on legal requirements, risk tolerance and dependents. Most U.S. states require auto liability insurance, and mortgage lenders require property insurance on the homes they finance. Above those requirements, a person with low risk tolerance buys broader coverage and pays higher premiums to avoid surprise costs. A person with higher risk tolerance buys less coverage or chooses higher deductibles and keeps the money saved on premiums. That person pays more of any loss out of pocket. Dependents increase the need for family health coverage, insurance on more vehicles and more life insurance. Premiums fall with less risky behavior: a clean driving record, not smoking.
For example, collision and comprehensive coverage on a $2,700 car costs $79 a month, which is $948 a year. The largest possible payout is the car's $2,700 value minus a $500 deductible. For an owner with an emergency fund who could absorb losing the car, the numbers support declining collision and comprehensive coverage. Filing an at-fault liability claim for a $450 scrape on someone else's car can raise a young driver's premium by about $30 a month for three years. The total premium increase over three years is more than the $450 repair.
Buy insurance for losses too large to absorb. Hold savings for the losses you can absorb.
Part 4 of 4 Predatory Lending and Fraud
| Risk | Defense |
|---|---|
| Predatory lending: deceptive terms, aggressive sales pressure | Compare loan terms from several sources; resist pressure to agree quickly; see a nonprofit credit counselor before signing |
| Phishing, identity theft, online scams | Judge whether an offer is credible; refuse pressure to share personal or financial details by phone or online; freeze your credit; seek legal aid if a scam succeeds |
A windshield sign offers a $5,000 car for $99 down and 36 easy payments. The 24% interest rate appears only in the small print. In total, the buyer pays about $2,000 more than the $5,000 sticker price. A message that names a real-sounding insurer and demands an urgent payment is built to collect account details. Open your insurer's app yourself instead of tapping the link in the message. Your insurer's app shows whether the payment demand is real. Treat urgency as a warning sign.
Worked Examples
The All-In Cost of a Used Car
Compute the true purchase cost of a vehicle including tax and required fees.
An eleven-year-old hatchback is agreed at $2,700 from a retiring coworker. The state sales tax is 6 percent, title and registration cost $88, and a pre-purchase mechanic's inspection cost $130. The buyer has $650 of graduation gift money, eight automatic transfers of $300, and $30 left over from a festival trip. Does the funding cover the purchase?
- Agreed price
- $2,700
- State sales tax rate
- 6%
- Title and registration
- $88
- Inspection
- $130
- Gift money
- $650
- Automatic transfers
- 8 at $300
- Cash left from the trip
- $30
1. Compute the sales tax on the sale price.
Sales tax applies to the price of the item, so 0.06 times $2,700 is $162.
2. Add every cost the purchase actually required.
$2,700 plus $162 of tax plus $88 of title and registration plus $130 for the inspection is $3,080. The inspection counts: it was spent to make the purchase safely, whatever the outcome had been.
3. Total the funding available.
Eight transfers of $300 is $2,400. Adding $650 of gift money and $30 of leftover cash gives $3,080.
4. Compare funding to cost.
$3,080 of funding against $3,080 of cost leaves nothing borrowed and nothing owed.
Check answerHide answer
Answer
$3,080. The car costs $3,080 all in, which the saved funds cover exactly, with no loan.
Why it matters
A sticker price is not a purchase price. Sales tax, registration, and inspection are predictable and belong in the plan from the start, because a buyer who saves only to the sticker is $380 short at the counter and reaches for credit.
Is Collision Coverage Worth Buying?
Weigh an optional coverage against the maximum it could ever pay.
Liability-only coverage on the car costs $164 a month. Adding collision and comprehensive, with a $500 deductible, raises the quote to $243 a month. The car is worth $2,700. Decide whether the added coverage is worth buying, and state the condition under which declining it is responsible.
- Liability-only premium
- $164 per month
- Full coverage premium
- $243 per month
- Deductible on collision
- $500
- Value of the car
- $2,700
1. Find the extra monthly cost.
$243 minus $164 is $79 a month of additional premium for coverage on the policyholder's own car.
2. Annualize it.
$79 times 12 is $948 a year, paid whether or not a collision ever happens.
3. Find the most the coverage could ever pay.
A collision claim pays the value of the car minus the deductible: $2,700 minus $500 is $2,200. That is the ceiling, not the expected payment.
4. Compare the two figures honestly.
$948 a year buys a benefit capped at $2,200, so about two and a third years of premium equals the largest payment the coverage could ever make.
5. State the condition on the decision.
Declining collision means keeping the risk. It is defensible only if losing the car outright would not break the household, which requires savings roughly the size of the car's value.
Check answerHide answer
Answer
Decline the collision coverage and keep the risk. Declining full coverage saves $948 a year against a benefit capped at $2,200, and it is the right call only for an owner who could absorb the loss of the car.
Why it matters
Insurance is worth buying for losses that would be unrecoverable, not for losses a household can cover itself. The same arithmetic points the other way on liability coverage, where the possible loss has no ceiling, which is why the law requires it and no one sensible declines it.
Claim It or Pay It Yourself?
Compare the cost of filing a covered claim against paying the loss directly.
Backing out of a parking space, a driver scrapes a parked sedan. The other car's repair estimate is $450, and the liability policy covers exactly this. An at-fault claim would raise the premium by about $30 a month for roughly three years. Both drivers agree on the facts, the loss sits below the state's reporting threshold, and the policy's notice rules are satisfied. Which costs less?
- Repair estimate
- $450
- Premium surcharge if claimed
- about $30 per month
- Surcharge duration
- about 36 months
- Emergency fund balance
- $1,814
1. Price the claim path.
The surcharge runs $30 a month for about 36 months, so filing costs about $1,080 in higher premiums.
2. Price the direct-payment path.
Paying the repair costs exactly the estimate, $450, and the premium is untouched.
3. Compare them.
$1,080 against $450 makes the claim about $630 more expensive, and more than twice the repair.
4. Check that the money exists.
Paying directly only works if the fund can absorb it. $1,814 minus $450 leaves $1,364, still a working emergency fund.
Check answerHide answer
Answer
Pay the $450 directly. Paying the repair costs $450 against roughly $1,080 of added premium, so the cheaper move is to pay it and leave the policy alone.
Why it matters
A policy covering a loss is not a reason to claim it. The real price of a small at-fault claim is the surcharge that follows, and an emergency fund is what makes the cheaper choice available. Note that this only holds where reporting rules and the policy's own notice terms allow it.
The True Cost of a Buy-Here-Pay-Here Loan
Compute the total paid on a high-rate car loan and compare it to the sticker price.
A lot advertises a $4,995 car for $99 down and 36 monthly payments, with 24 percent annual interest disclosed in small print. That is 2 percent per month on the financed balance, giving a payment of $192.08. Find the total paid and how far it exceeds the advertised price.
- Advertised price
- $4,995
- Down payment
- $99
- Annual rate
- 24%
- Monthly rate
- 2%
- Term
- 36 months
- Monthly payment
- $192.08
1. Find the amount actually financed.
$4,995 minus the $99 down payment leaves $4,896 borrowed.
2. Confirm the payment against the loan terms.
At 2 percent a month over 36 months, the level payment that clears $4,896 is $192.08, which matches the advertised figure.
3. Total everything paid.
36 payments of $192.08 is $6,914.88, and adding the $99 down payment gives $7,013.88.
4. Compare the total to the sticker.
$7,013.88 minus $4,995 is $2,018.88 of interest, about 40 percent more than the advertised price.
Check answerHide answer
Answer
$7,013.88. The advertised $4,995 car costs $7,013.88, which is $2,018.88 above the sticker.
Why it matters
Predatory offers advertise the monthly payment and bury the rate, because a payment sounds small and a total does not. The defenses are procedural: compute the total before signing, compare terms from several lenders, refuse to be rushed, and take anything unclear to a nonprofit credit counselor.
Building and Then Using an Emergency Fund
Track an emergency fund from zero to goal and through its first withdrawal.
A saver targets a $1,500 emergency fund held in an insured credit union account paying 4.0 percent annual yield. June and July each sweep a $236 budget buffer into it. In August the $300 weekly transfer that had funded the car is redirected to the fund for four Fridays, and August's $42 buffer follows. September adds $100, then a $450 repair is paid out of the fund, and $100 a month rebuilds it through December. Track the balance.
- Goal
- $1,500
- June buffer
- $236
- July buffer
- $236
- August Friday transfers
- 4 at $300
- August buffer
- $42
- Monthly savings line from September
- $100
- Repair paid from the fund
- $450
1. Add the two summer buffers.
$236 plus $236 is $472 carried into August.
2. Add August's redirected transfers.
Four Fridays at $300 is $1,200, which brings the balance to $1,672 before the month-end sweep, so the $1,500 goal is passed on the fourth August transfer.
3. Sweep August's buffer.
Adding the $42 August buffer gives $1,714 on September 1.
4. Add September's savings line, then pay the repair.
$1,714 plus $100 is $1,814, and paying the $450 repair leaves $1,364, below goal but fully functional.
5. Rebuild it.
Three more monthly deposits of $100 through December bring the fund to $1,664, back above the goal.
6. Notice what the interest does and does not do.
At 4.0 percent a year, $1,500 earns about $5 a month. Useful, but the account's job is to hold the money reachable and safe, not to grow it.
Check answerHide answer
Answer
$1,664. The fund reaches $1,714, absorbs a $450 repair, and rebuilds to $1,664 by the end of December.
Why it matters
An emergency fund is not idle money; it is what licenses every decision to keep a risk rather than insure it. Rebuilding it on a schedule after a withdrawal is part of the plan, because a fund that is used once and never refilled protects nothing next time.
Key Terms
- Auto Insurance
- Beneficiaries
- Claim
- Coverage
- Deductible
- Disability Insurance
- Emergency Fund
- Extended Warranty
- Health Insurance
- Homeowners Insurance
- Insurable Risks
- Insurance
- Insurance Fraud
- Liability
- Liability Risk
- Life Insurance
- Personal Risk
- Policy
- Premium
- Property Risk
- Quantifiable
- Renters Insurance
- Risk (personal finance)
- Risk Tolerance
- Service Contract
- Statistically Predictable
Practice Questions
4 questions. Nothing here is recorded or scored.
Unit 5 is not assessed on the AP Business with Personal Finance Exam. The exam covers Units 1 through 4. Unit 5 supports the Financial Advisor Project and your own money decisions.
- Question 15.2.D.1, 5.2.D.2
Corrine Vaughn's First Car
Corrine Vaughn has saved 1,800 dollars toward her first car, adding 120 dollars a month since spring. Pelham Motors has a used sedan on the lot at a 7,200 dollar sticker price, and the salesperson has offered to finance it in the showroom: 400 dollars down and 48 monthly payments of 200 dollars, with the annual rate printed at the bottom of the last page. He has also offered a 900 dollar service contract that would pay for covered repairs for three years, and he says both offers hold only until the lot closes tonight. Sandhill Credit Union preapproved Corrine last week for the same car at 400 dollars down and 48 monthly payments of 175 dollars, and she has not yet put the two offers beside each other. A mechanic she trusts told her that the repair this model most often needs after 100,000 miles runs between 1,900 and 3,000 dollars.
Which conclusion about the two financing offers is supported by the figures?
- A.Over its term the showroom offer costs 1,200 dollars more than the credit union offer.
- B.The showroom offer costs 25 dollars more, the gap between the two monthly payments.
- C.The two offers cost the same, since both take 400 dollars down on the same used vehicle.
- D.The showroom offer costs 2,800 dollars more over its full term than the credit union offer.
Check answerHide answer
Answer: A
- A.
- Correct. Putting loan terms from more than one source side by side is the defense the framework names against a lending offer built on pressure and small print, and the comparison has to be on total cost rather than on payment size. The showroom offer is 400 dollars down plus 48 payments of 200 dollars, which is 10,000 dollars. The credit union offer is 400 dollars down plus 48 payments of 175 dollars, which is 8,800 dollars. Same car, same term, same money down, and 1,200 dollars between them, sitting behind a rate printed at the bottom of the last page.
- B.
- This reads the gap one month at a time, which is exactly how a showroom quote is built to be read. A 25-dollar difference is easy to wave off; carried across 48 payments it is the whole 1,200 dollars.
- C.
- The down payment and the sticker price are the two things the offers share, so they cannot be what separates them. What separates them is the interest rate, and the showroom's is the number the salesperson did not lead with.
- D.
- 2,800 dollars is a real figure in this deal, but it answers a different question. It is what the showroom offer adds on top of the 7,200 dollar sticker, the finance charge on that loan. The credit union loan carries a finance charge of its own, 1,600 dollars, so the distance between the two offers is the difference between those charges.
- Question 25.2.B.6, 5.2.C.3
Which of the following would most support Corrine's buying the 900 dollar service contract?
- A.She has been setting aside 120 dollars a month, so the fee equals about eight months of saving.
- B.The salesperson has told her the service contract is available only until the lot closes tonight.
- C.A repair in the range her mechanic named would run past her whole savings account.
- D.Pelham Motors sells the contract, so the dealership would handle any covered repair itself.
Check answerHide answer
Answer: C
- A.
- Whether she can afford the fee is a different question from whether the risk is worth handing off. Eight months of saving would buy the contract either way, and it would buy it just the same on a car whose worst repair she could pay for out of pocket. What settles the decision is the size of the loss measured against the savings that would have to meet it.
- B.
- A closing-time deadline is a sales tactic, not information about the car. Pressure to agree quickly is one of the things the framework tells buyers to resist, and a contract worth 900 dollars tonight is worth about the same on Saturday.
- C.
- Correct. A service contract or extended warranty on an expensive purchase works like insurance: a fee paid now in exchange for repair bills later, which is the same trade a premium makes. That trade earns its price when the loss it covers is larger than the buyer can absorb, and the repair her mechanic named starts at 1,900 dollars against an account holding 1,800 before the 400 dollar down payment comes out of it. This is the line between a risk to transfer and a risk to keep: buy coverage for losses too large to absorb, hold savings for the ones that only sting.
- D.
- Who performs the repair says nothing about whether the coverage is worth its price. The seller being the same dealership is a convenience at most, and it is a reason to read what the contract actually covers rather than a reason to sign it.
- Question 35.2.A.2
A small insurer is considering a new policy that would reimburse restaurant owners for food spoiled during a power outage. Which of the following would most support the decision to offer the policy?
- A.Owners in the area say they would pay a monthly premium for coverage against spoiled stock.
- B.The insurer already writes property and liability policies for restaurants on that grid.
- C.The insurer can price the premium high enough to stay ahead of whatever the payouts reach.
- D.Ten years of records show how often outages spoil stock and what the lost food is worth.
Check answerHide answer
Answer: D
- A.
- Demand and insurability are separate questions. Willingness to pay tells the insurer a market exists, and it says nothing about how often the loss happens or what it costs, which is what has to be known before a policy can be priced at all.
- B.
- An existing book of business is a sales advantage, not evidence about the risk. Here it cuts the other way if anything, because a single outage on that grid would hit many of those restaurants in the same hour.
- C.
- This puts the pricing ahead of the measuring. A premium can be set only once the insurer knows how often the loss occurs and what it costs, so the option quietly assumes the very thing the insurer still has to find out.
- D.
- Correct. An insurable risk is a potential loss that arrives by chance, an accident or a weather event rather than a choice, and it must also be quantifiable and statistically predictable, meaning the insurer can estimate both the cost of a loss and how likely it is. Spoiled stock after an outage arrives by chance rather than by the owner's decision, and the records supply the other two halves of the test: the frequency of outages long enough to spoil food, and the value of the food lost.
- Question 45.2.C.6
Which of the following best identifies conduct that counts as insurance fraud?
- A.A driver raises her deductible to 1,000 dollars for a lower premium and pays small repairs herself.
- B.An agent tells a shopper a policy covers burst-pipe water damage the policy actually excludes.
- C.A homeowner files a claim for storm damage and the insurer pays less than the repair estimate.
- D.A shopper collects quotes from three insurers and moves her policy to the one charging least.
Check answerHide answer
Answer: B
- A.
- Choosing a higher deductible and absorbing small repairs is a risk tolerance decision the framework describes rather than a misrepresentation. She is telling the insurer exactly what she intends to do, and the lower premium is the price of the risk she agreed to keep.
- B.
- Correct. Insurance fraud is misrepresentation or a falsified claim, and the rule runs in both directions: a policyholder who lies to an insurer commits it, and so does a seller who misrepresents what a policy or a benefit covers. Telling a shopper the policy pays for a loss the contract excludes is the seller's half of that rule, and it is a crime whether or not a claim is filed later.
- C.
- A payment smaller than a repair estimate is ordinary claims handling. The deductible comes out first, and an insurer reimburses covered costs rather than whatever figure a shop writes down. Disagreeing about an amount is a dispute; fraud requires that someone misrepresented something.
- D.
- Comparison shopping is what the framework tells buyers to do. Moving a policy to the insurer charging least for the coverage you want is the intended result of that shopping.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →7 Common Mistakes on 5.2
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
5.2.A.1 · 5.2.A.2 · 5.2.A.3 · 5.2.A.4 · 5.2.A.5 · 5.2.B.1 · 5.2.B.2 · 5.2.B.3 · 5.2.B.4 · 5.2.B.5 · 5.2.B.6 · 5.2.C.1 · 5.2.C.2 · 5.2.C.3 · 5.2.C.4 · 5.2.C.5 · 5.2.C.6 · 5.2.D.1 · 5.2.D.2 · 5.2.D.3