5.3 Saving and Investing for Education, Housing, and Retirement Goals
Saving and investing toward education, housing, and retirement, and how compounding, fees, taxes, and your own biases shape what you end up with.
Part 1 of 3 Three Long Goals
Unit 5 covers personal finance you will use for life. The AP exam covers Units 1 to 4. Long-term goals usually mean postsecondary education, a home and retirement, with charitable giving alongside. Each goal needs a funding plan. The funding plan sets how much money the goal needs, where the money comes from and the time horizon, which is how many years the saving runs.
| Goal | Funded by | Worth knowing |
|---|---|---|
| Postsecondary education | Savings, scholarships and grants, work-study, student loans; a 529 plan for a family with time | Where and what to study depend on career goals and funding; federal loans tend to carry lower rates and better repayment terms than private ones, and some are subsidized |
| A home | A down payment from savings plus a mortgage | Where to live and whether to rent or buy depend on preference and funding; buying means qualifying for a mortgage, and the payment depends on the loan size, the repayment period and the rate; a fixed-rate mortgage holds the payment steady, an adjustable-rate mortgage can move with market rates |
| Retirement | Social Security, employer plans such as a 401(k), personal investments such as an IRA, continued earnings | When to retire and where to live depend on preference, health and funding |
| Charitable giving | One-time gifts, recurring donations, legacy contributions | Chosen by mission and impact; may carry a tax deduction |
Couples who pool their finances argue less about money when the long-range goals are discussed and jointly owned. Automated savings plans and payroll deduction for retirement accounts make saving easier, because the saver makes the decision once instead of every payday. The voluntary deduction lines on a first pay stub, which read zero, are where those retirement contributions will eventually appear. A 529 plan opened early for a child does the same work for tuition.
Part 2 of 3 What Decides the Return
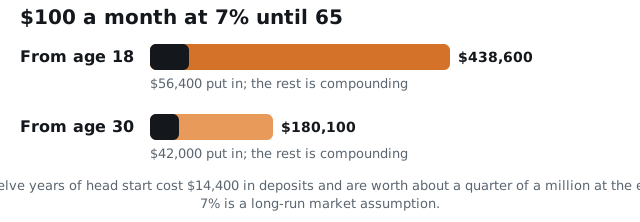
Compounding means returns earn returns, and the longer the money is invested, the more it compounds. $100 a month from age 18 to 65 at an assumed 7% long-run return ends near $438,600, against $56,400 put in. The same habit begun at 30 ends near $180,100. The 7% is an assumption drawn from market history.
| Factor | How the factor cuts the return |
|---|---|
| Fees | Transaction, management and advice fees all cut the return; stocks and bonds are usually bought through a broker, and discount firms charge less and advise less than full-service ones. A 1% annual fee on the $100-a-month example above costs about $125,500 of the ending balance |
| Taxes | Interest, dividends and capital gains are taxed, so tax treatment is part of choosing an asset |
| Inflation | Inflation cuts purchasing power, so a nominal return overstates the gain and a real return, measured after inflation, states it correctly |
| Behavior | Overconfidence leads investors to take unnecessary risk; loss aversion leads investors to sell while prices are down, which makes the loss final |
Worked Examples
Net Pay and a Balanced Fall Budget
Rebuild a budget after hours change, and solve for the buffer.
School starts and the job goes back to 18 hours a week at $14.00. Payroll and state rates are unchanged and the federal line is zero at this pay level. The fall plan carries insurance $164, gas $90, phone $40, a college payment plan $175, food and fun $120, gifts $20, a Roth contribution $100, and emergency-fund savings $100. The household contribution is waived. Find the buffer.
- Hours per week
- 18
- Hourly wage
- $14.00
- Social Security rate
- 6.2%
- Medicare rate
- 1.45%
- State income tax rate
- 2.5%
- Federal withheld
- $0.00
- Named budget lines
- $164, $90, $40, $175, $120, $20, $100, $100
1. Find weekly gross pay.
18 hours at $14.00 is $252.00.
2. Withhold the three active lines.
Social Security is 0.062 times $252.00, or $15.62. Medicare is 0.0145 times $252.00, or $3.65. State tax is 0.025 times $252.00, or $6.30.
3. Find weekly net pay.
$252.00 minus $25.57 is $226.43.
4. Set the monthly planning figure.
Four checks of $226.43 is $905.72, so the plan is built on an even $905.
5. Total the named lines and solve for the buffer.
$164 plus $90 plus $40 plus $175 plus $120 plus $20 plus $100 plus $100 is $809, so the buffer is $905 minus $809.
Check answerHide answer
Answer
$96. Net pay is $226.43 a week, the monthly plan is $905, and the buffer is $96.
Why it matters
Income fell by more than half, and the plan was rebuilt from the new net pay rather than trimmed from the old one. Notice that three lines fund three different futures at once: this semester, the next emergency, and a retirement forty seven years out.
What a Semester Actually Costs
Compute out-of-pocket education cost after aid, and convert it to a monthly payment.
In-district tuition and fees are $1,850 a semester. A need-based grant covers $1,400 of it, and books cost $250. The college offers an interest-free payment plan spread over the four months of the term. Also compare the cost of a room near campus at $700 a month against living at home for two years.
- Tuition and fees
- $1,850 per semester
- Need-based grant
- $1,400
- Books
- $250
- Payment plan length
- 4 months
- Room near campus
- $700 per month
- Time living at home
- 24 months
1. Subtract aid that is never repaid.
A grant reduces the bill outright, so $1,850 minus $1,400 leaves $450 of net tuition.
2. Add the costs aid did not cover.
$450 of net tuition plus $250 of books is $700 out of pocket for the semester.
3. Convert it to a monthly payment.
The interest-free plan spreads $700 across 4 months, which is $175 a month, and because there is no interest the total paid equals the total owed.
4. Price the housing decision separately.
A room at $700 a month for 24 months is $16,800 that living at home does not spend, which dwarfs the tuition figure.
5. Read the two numbers together.
The funding mix here is savings, a grant, and a job, with no borrowing at all. Where a student does have to borrow, the federal programs generally charge less interest and repay on gentler terms than a private lender offers.
Check answerHide answer
Answer
$700 per semester, paid at $175 a month. Out-of-pocket cost is $700 a semester, or $175 a month on the interest-free plan, and living at home avoids about $16,800 of housing across two years.
Why it matters
The sticker price is rarely the price. Aid that is never repaid comes off first, housing usually outweighs tuition at a community college, and the sequence of savings, grants, and work before loans is what keeps a degree from being financed.
What a Hundred Dollars a Month Becomes
Compute the future value of a monthly contribution and price the cost of waiting.
A saver contributes $100 on the first Friday of every month from age 18 to age 65, assuming a long-run return of 7 percent compounded monthly. Compute the ending balance, then compute what the same habit produces if it starts at age 30 instead. Seven percent is an assumption drawn from long-run market history, not a promise.
- Monthly contribution
- $100
- Assumed annual return
- 7%
- Compounding
- monthly
- Years from age 18
- 47
- Years from age 30
- 35
1. Convert the annual rate to a monthly rate and count the periods.
7 percent a year compounded monthly is 0.07 divided by 12, about 0.005833 a month. From 18 to 65 is 47 years, or 564 months.
2. Apply the future value of a series.
The balance is the payment times the growth factor, one plus the rate raised to the number of months, minus one, divided by the rate.
3. Evaluate it for 564 months.
The growth factor works out to about 4,386, so $100 a month ends near $438,600.
4. Separate contributions from growth.
564 contributions of $100 is $56,400 of the saver's own money, so the remaining $382,200 is compounding.
5. Rerun it starting twelve years later.
From 30 to 65 is 420 months, and the same $100 a month ends near $180,100 on $42,000 contributed.
6. Price the delay.
The difference is about $258,500 of ending balance for $14,400 of extra contributions, which is what those twelve years of compounding were worth.
7. Sanity check the intuition on a single dollar.
One dollar left alone at 7 percent for 47 years multiplies by about 24, which is the same fact stated without a contribution schedule.
Check answerHide answer
Answer
about $438,600. The plan ends near $438,600 on $56,400 contributed. Starting at 30 instead ends near $180,100, so twelve years of delay cost roughly $258,500.
Why it matters
Time, not contribution size, does most of the work, and that is the entire argument for starting a retirement account at a wage that feels too small to matter. The assumed return is a historical average and any real path is far bumpier.
What a One Percent Fee Costs
Quantify the lifetime cost of a one percent annual fee on an investment plan.
Take the same $100 a month for 564 months, but assume a 1 percent annual advisory or fund fee, so the net return is 6 percent rather than 7 percent. Compute the ending balance and the cost of the fee.
- Monthly contribution
- $100
- Gross assumed return
- 7%
- Annual fee
- 1%
- Net return
- 6%
- Months
- 564
1. Restate the return after the fee.
A 1 percent annual fee turns an assumed 7 percent gross return into a 6 percent net return, or 0.005 a month.
2. Apply the same future value formula.
Using the same series formula at 0.005 over 564 months, the ending balance is near $313,200.
3. Subtract to price the fee.
About $438,600 at 7 percent against about $313,200 at 6 percent is a gap of roughly $125,500.
4. Compare that to what was contributed.
The fee costs more than twice the $56,400 the saver ever put in, without any single charge ever looking large.
Check answerHide answer
Answer
about $125,500. A 1 percent annual fee costs roughly $125,500 of the ending balance, reducing about $438,600 to about $313,200.
Why it matters
Fees compound exactly as patiently as returns do, which is why an expense ratio measured in hundredths of a percent is worth checking and why cost sits alongside licensing, certifications, education, and experience when choosing an adviser.
An Education Account Started at Birth
Compute what a small monthly education contribution grows to over eighteen years.
A family opens a tax-advantaged education savings account when a child is born and contributes $50 a month until the child turns 18, assuming 6 percent compounded monthly. How much is in the account, and how much of it was contributed?
- Monthly contribution
- $50
- Assumed annual return
- 6%
- Compounding
- monthly
- Years
- 18
1. Count the periods and the monthly rate.
18 years is 216 months, and 6 percent a year compounded monthly is 0.005 a month.
2. Apply the future value of a series.
Using the same series formula with a $50 payment, the balance at 18 is about $19,367.
3. Find the amount contributed.
216 payments of $50 is $10,800 of family money.
4. Separate growth from contribution.
$19,367 minus $10,800 is about $8,567 of growth, roughly 79 percent on top of what was put in.
5. Compare it to a semester bill.
Against a $700 out-of-pocket semester, that balance would cover many terms outright, which is the point of starting a long horizon early.
Check answerHide answer
Answer
about $19,367. Eighteen years of $50 a month grows to about $19,367 on $10,800 contributed.
Why it matters
The same compounding argument that governs a retirement account governs an education account, only over eighteen years instead of forty seven. The lesson for a student already at eighteen is not regret; it is that the longest horizon they still control is retirement, and that one starts today.
Key Terms
- 401(k)
- 529 Plan
- Adjustable-Rate Mortgage
- Asset Allocation
- Bond
- Capital Gains Tax
- Charitable Giving
- Compounding
- Diversification
- Down Payment
- ETF
- Fixed-Rate Mortgage
- Investment
- IRA
- Loss Aversion
- Mortgage
- Mutual Fund
- Nominal Return
- Overconfidence
- Real Return
- Retirement
- Return
- Risk Tolerance
- Savings Rate
- Savings Vehicles
- Stock
- Stock or Bond Index
- Time Horizon
Practice Questions
4 questions. Nothing here is recorded or scored.
Unit 5 is not assessed on the AP Business with Personal Finance Exam. The exam covers Units 1 through 4. Unit 5 supports the Financial Advisor Project and your own money decisions.
- Question 15.3.A.3
The Havlik Household
Nadine and Orrin Havlik rent an apartment and have saved $24,000 toward a down payment, which sits in a federally insured savings account paying 3 percent a year. They expect to buy a house within the next year. A lender has offered them two loans on the same $180,000 they would need to borrow, each repaid over 30 years. A fixed-rate loan at 6.5 percent would hold their monthly payment at $1,138 for the full 30 years. An adjustable-rate loan starting at 5.25 percent would set the payment at $994 a month for five years, after which the rate resets each year to whatever the market rate is then. Nadine favors the adjustable loan for its lower starting payment, and she has also suggested moving the $24,000 into a stock fund that returned 19 percent last year so the down payment grows while they shop. Orrin wants to understand both ideas before they sign anything.
The two loans would borrow the same $180,000 over the same 30 years. Which of the following best explains why the adjustable loan's payment starts $144 a month lower?
- A.The adjustable loan charges a lower interest rate during its first five years.
- B.The adjustable loan spreads its repayment across more years than the fixed loan.
- C.The adjustable loan asks for a larger down payment, so less has to be borrowed.
- D.The adjustable loan collects no interest during the years before its first reset.
Check answerHide answer
Answer: A
- A.
- Correct. Three inputs decide a monthly mortgage payment: how much is borrowed, how many years the repayment runs, and the interest rate charged. These two offers hold the first two steady at $180,000 and 30 years, so the rate is the only input left to move, and 5.25 percent against 6.5 percent is what puts the payment at $994 instead of $1,138. The trade is written into the second loan: that rate holds only through year five, after which it resets each year to the market rate, so the $144 of monthly room is bought with the risk of a higher payment later.
- B.
- The passage gives both loans a 30-year repayment period, so the term cannot be what separates them. A longer repayment period does lower the monthly payment, which is why this reads as plausible, and it also stretches the interest over more years and raises the total paid.
- C.
- The Havliks borrow the same $180,000 either way, and their $24,000 down payment does not change between the two offers. A larger down payment would shrink the loan and the payment with it, but that is a lever they pull by saving more, not a difference between these two loans.
- D.
- Both loans charge interest from the first payment onward. A reset changes the rate the interest is figured at; it does not decide whether interest is charged at all, and the early years of a mortgage are when interest takes its largest share of each payment.
- Question 25.3.C.2, 5.3.B.3
Orrin argues that the $24,000 should stay in the insured savings account until the Havliks buy. Which of the following best supports his position?
- A.A stock fund that returned 19 percent last year is unlikely to repeat that next year.
- B.A drop in the fund's value the month before closing would shrink the down payment.
- C.An insured savings account pays a higher return than a stock fund over long periods.
- D.The stock fund charges management fees, and fees reduce what an investor keeps.
Check answerHide answer
Answer: B
- A.
- Last year's 19 percent is a weak forecast of next year's, which is worth knowing, but it is not what settles this decision. Even a fund with a strong expected average would be the wrong home for money the Havliks may need back on a date they do not control.
- B.
- Correct. Time horizon is how long money can stay invested before it is needed, and the horizon on this $24,000 is under a year. An investor with decades ahead can hold a stock fund through a downturn and wait for the value to come back; a buyer who owes a down payment on closing day sells at whatever the market offers that week, and a fund that gave back last year's gain in a bad month would leave the Havliks short of the house. The insured account pays only 3 percent, and that lower return is the price of knowing the full $24,000 is there on the day it is needed.
- C.
- This turns the risk-and-return ladder upside down. Insured accounts pay less, here 3 percent, precisely because a federal guarantee stands behind them, while stock funds are expected to pay more over long holding periods in exchange for the swings along the way. Orrin has the better case for this money, but the reason is timing rather than long-run returns.
- D.
- Fees are a real drag on return, and comparing them is worth doing before buying into any fund. Still, a management fee measured in fractions of a percent is small next to a market drop of ten or twenty percent in the month the money is needed, so it is not the strongest support for keeping the down payment out.
- Question 35.3.B.7
An investor holds a broad market fund for a retirement goal about thirty years away. The fund falls 14 percent over three weeks, and the investor sells the whole position, planning to buy back once prices recover. Which of the following best describes the cost of selling?
- A.The sale costs little, because a thirty-year horizon leaves time to make the money back.
- B.The sale raises the fund's management fee, since those fees are charged when shares sell.
- C.The sale shortens the investor's time horizon, which lowers the return the goal needs.
- D.The sale turns a paper decline into a realized loss and sits out any rebound.
Check answerHide answer
Answer: D
- A.
- A long horizon is what makes the sale avoidable, not what makes it cheap. The horizon only works on money that stays invested, and dollars pulled out at a 14 percent decline spend the recovery sitting in cash.
- B.
- This trades a management fee for a transaction cost. A management fee is charged against the balance held, year after year, whether or not shares are sold, and it is one of the ongoing costs that quietly reduce return over a long holding period.
- C.
- The horizon is set by when the money is needed, which is still about thirty years out, and a sale does not move that date. What the sale changes is how much of the balance is invested during those thirty years.
- D.
- Correct. While the fund is down only on paper, the shares are still owned and still ride whatever the market does next. Selling converts that decline into a loss the investor actually takes and parks the money on the sideline for the recovery, which is how loss aversion, the tendency to feel a loss more sharply than an equal gain, costs a long-horizon saver real money. Buying back once prices recover also asks the investor to spot a bottom that is clear only afterward.
- Question 45.3.B.6
A saver puts $4,000 into a one-year certificate of deposit that pays a nominal return of 5 percent. Prices rise 3 percent over that same year. Which of the following best describes what the certificate produced?
- A.It paid $200 of interest, and inflation left purchasing power unchanged.
- B.It paid $120 of interest, the share of the 5 percent that inflation leaves.
- C.It paid $200 of interest, a real return of roughly 2 percent after inflation.
- D.It paid $320 of interest, the 5 percent it pays plus the 3 percent that prices rose.
Check answerHide answer
Answer: C
- A.
- The interest figure is right and the conclusion is not. Purchasing power would sit flat only if the two rates matched, and a 5 percent return against 3 percent inflation leaves the saver about two points ahead of prices.
- B.
- This subtracts in the wrong place. Inflation comes off the return rate, not off the interest payment, so the certificate still credits the full $200; what shrinks is what those dollars buy. Taking 3 percent of $4,000 answers a question the situation did not ask.
- C.
- Correct. A nominal return is the rate before any adjustment, so 5 percent of $4,000 is $200 of interest actually credited to the account. The real return subtracts inflation from the nominal return to show what the money gained in buying power: 5 percent less 3 percent is about 2 percent. Both figures are true at once, which is why investors read them together, and it is also why a savings rate below the inflation rate loses ground even while the balance climbs.
- D.
- Adding inflation to the return doubles the error. Rising prices work against a saver, so inflation is subtracted from the nominal return rather than added to it, and the certificate pays its stated 5 percent whatever prices do.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →6 Common Mistakes on 5.3
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
5.3.A.1 · 5.3.A.2 · 5.3.A.3 · 5.3.A.4 · 5.3.A.5 · 5.3.A.6 · 5.3.A.7 · 5.3.B.1 · 5.3.B.2 · 5.3.B.3 · 5.3.B.4 · 5.3.B.5 · 5.3.B.6 · 5.3.B.7 · 5.3.C.1 · 5.3.C.2 · 5.3.C.3 · 5.3.C.4 · 5.3.C.5 · 5.3.C.6