3.4 Business Expenses
Startup costs and the expenses of operating a business.
Part 1 of 3 Startup Costs
Startup costs include two kinds of cost. One-time expenditures are paid a single time to launch a business or product. Initial expenses are the first operating expenses a founder pays while setting up. The two kinds behave differently once the business opens.
| One-time expenditures | Initial expenses | |
|---|---|---|
| What they are | Legal fees, incorporation and licensing fees, and in some cases equipment | Occupancy, research and development, marketing, insurance, the first inventory |
| What happens after launch | They stop | They become recurring costs: the first month's rent becomes every month's rent, the first stock becomes a weekly reorder |
| For a drink shop | $150 filing fee, $200 license, $350 health permit, the machines | $2,500 of first-month rent, $1,800 of opening stock, $1,000 of signage and launch promotion |
Equipment is usually the largest one-time expenditure by far. The cost of equipment is usually the reason a founder looks for outside money. Research and development scales with the industry. Weeks of test batches on a home stove and years of laboratory work before a drug launch are the same category at very different sizes.
The word initial says when an expense starts. Most initial expenses become recurring costs after launch.
Part 2 of 3 Two Independent Axes
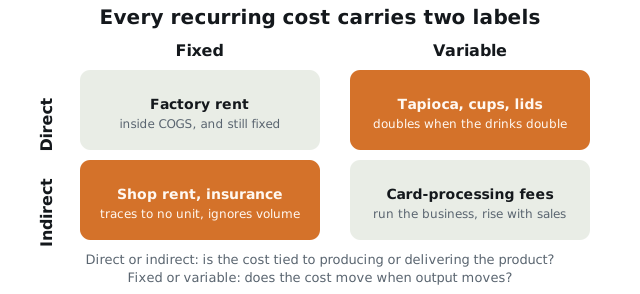
Once a business operates, each recurring cost picks up two labels. Direct costs are tied to producing or delivering specific goods or services. Indirect costs, also called operating expenses, pay for running the rest of the business. Fixed expenses hold steady whatever the output; variable expenses rise as output rises. The running example is a drink shop that sells about 3,000 drinks in a typical month at $6.00, with $1.50 of ingredients in each. Rent is $2,500 in a month of 1,800 drinks and $2,500 in a month of 4,200. Ingredients at $1.50 a drink cost $2,700 in the month of 1,800 drinks and $6,300 in the month of 4,200 drinks.
Part 3 of 3 COGS, Cost of Sales and Operating Expenses
| Business | Name | What goes in |
|---|---|---|
| Makes goods | Cost of goods sold (COGS) | Raw materials, production supplies, production wages and benefits, the cost of running the plant. Parts can be fixed (factory rent) or variable (materials) |
| Provides a service | Cost of sales | Direct labor, travel, materials used to deliver the service: hours on site, the drive across town, the supplies in the van |
Operating expenses are the recurring indirect costs, typically fixed: occupancy, salaries and benefits for office and sales staff, marketing and advertising, supplies, utilities, maintenance, insurance. A small shop's monthly operating expenses might be $2,500 rent, $6,200 wages, $400 utilities, $300 marketing, $250 insurance and $250 supplies, for a total of $9,900. The $9,900 total stays about the same whether the shop sells 1,800 drinks or 4,200 drinks in a month. In a slow month, the shop still pays about $9,900 from fewer sales, so profit falls.
Insurance protects against losses from accidents, injuries and property damage. Some insurance is required, such as workers' compensation insurance; many kinds are optional. One owner buys a liability policy and declines coverage on the machines; another buys both. The two owners make different choices because they have different risk tolerance. Consumers make the same kind of choice about renter's insurance or collision coverage on an old car.
Worked Examples
Totalling the startup cost of a new shop
Add one-time expenditures and initial expenses into a single startup figure.
A founder opening a drink shop holds a folder of quotes. Sort them into one-time expenditures and initial expenses, then total the launch.
- One-time fees
- $150 + $200 + $350
- Equipment
- $15,000
- Lease deposit
- $2,500
- Opening inventory
- $1,800
- Opening marketing
- $1,000
1. Sum the one-time fees
The three paperwork lines add up first. $150 plus $200 plus $350 is $700.
2. Add the equipment package
Equipment is the other one-time expenditure. $700 plus $15,000 is $15,700.
3. Add the initial expenses
The deposit, the first inventory, and the opening marketing come to $2,500 plus $1,800 plus $1,000, which is $5,300.
4. Total the launch
Combine the two halves. $15,700 plus $5,300 is $21,000.
Check answerHide answer
Answer
$21,000. Launching this shop costs $21,000 before a single unit is sold, split into $15,700 that is genuinely one-time and $5,300 that starts a recurring bill.
Why it matters
The total matters less than the split. Every dollar in the second group came back the next month as rent, as a reorder, and as a marketing budget, which is why a founder who plans only for the total runs out of money in month two.
Adding up a month of operating expenses
Total the recurring indirect costs of running a business for one month.
The same shop, three years in, carries six operating lines every month. Total them, then check what happens to that total when volume changes.
- Rent
- $2,500
- Staff wages
- $6,200
- Utilities
- $400
- Marketing
- $300
- Insurance
- $250
- Supplies and miscellaneous
- $250
1. Add the six lines
Work down the column. $2,500 plus $6,200 is $8,700; plus $400 is $9,100; plus $300 is $9,400; plus $250 is $9,650; plus $250 is $9,900.
2. Test the total against a slow month
Sales of 1,800 units do not change rent, insurance, or the marketing budget, so the same $9,900 has to be paid.
3. Test it against a peak month
Sales of 4,200 units barely move it either, apart from extra shifts inside the wage line, so the total holds near $9,900.
Check answerHide answer
Answer
$9,900 a month. Six operating lines total $9,900, and that figure is nearly the same in the worst month of the year and the best one.
Why it matters
Fixed overhead is why a slow month hurts out of proportion to the sales it lost. The revenue fell by more than half between the peak and the trough; the overhead did not move.
Scaling a variable cost across three months
Compute a variable cost at three volumes and contrast it with a fixed cost over the same range.
Ingredients and packaging cost $1.50 per unit. Rent is $2,500 a month. Compute both costs for a trough month of 1,800 units, a typical month of 3,000, and a peak month of 4,200.
- Variable cost per unit
- $1.50
- Monthly rent
- $2,500
- Trough volume
- 1,800 units
- Typical volume
- 3,000 units
- Peak volume
- 4,200 units
1. Compute the variable cost at each volume
Multiply the per-unit cost by each volume. 1,800 times $1.50 is $2,700. 3,000 times $1.50 is $4,500. 4,200 times $1.50 is $6,300.
2. Note what rent does across the same three months
Rent is charged at $2,500 in all three, because it is fixed with respect to output.
3. Measure how far each cost moved
The variable cost rose from $2,700 to $6,300, which is a $3,600 swing. Rent moved by $0.
Check answerHide answer
Answer
$2,700, $4,500, and $6,300 of variable cost against $2,500 of rent every month. The variable cost more than doubles across the range while the fixed cost does not move at all.
Why it matters
This is the whole reason the fixed and variable labels exist. Forecasting next month means projecting only the lines that respond to volume, and carrying the rest across unchanged.
Key Terms
Practice Questions
6 questions. Nothing here is recorded or scored.
- Question 13.4.A.2, 3.4.A.3
Crux House Climbing
Andre Holt is eight weeks from opening Crux House Climbing, an indoor climbing gym in a leased warehouse. He has already paid the state incorporation fee and the city business license, put down a lease deposit and the first month's rent, and hired a crew to build the climbing walls. Before opening day he still needs an opening stock of rental shoes, harnesses, and chalk bags, a month of advertising, and the liability insurance policy his landlord requires before the first climber leaves the ground. Once the gym opens, Andre will pay route setters who build and reset the climbing routes, an office manager who handles memberships and billing, monthly rent and utilities, and a steady resupply of chalk, athletic tape, and shoe cleaning spray. He is still deciding whether to add an optional policy covering damage to the walls and padding, or to accept that risk and keep the premium.
Which of Andre's launch costs is best described as a one-time expenditure rather than an initial expense that continues once the gym is operating?
- A.The first month of rent on the leased warehouse space.
- B.The opening stock of rental shoes, harnesses, and chalk bags.
- C.The first premium payment on the liability insurance policy.
- D.The state incorporation fee and the city business license.
Check answerHide answer
Answer: D
- A.
- Occupancy expense, and rent bills every month forever. It is a startup cost, but it lands in the initial-expense bucket, the bills that continue for the life of the business.
- B.
- Initial inventory. Rental shoes wear out, so the opening stock becomes a standing reorder line rather than a one-time purchase.
- C.
- The first premium starts coverage before opening day, but insurance is an initial expense: the policy keeps billing for as long as the gym operates, alongside occupancy, marketing, and inventory.
- D.
- Correct. Startup costs are everything paid to launch a business, and they split into two buckets that behave differently. One-time expenditures, meaning legal fees, incorporation and licensing fees, and in some cases equipment, are paid once; the state and the city cash Andre's checks exactly once. Initial expenses are the operating bills that start before opening day and then continue for the life of the business. All four choices are startup costs, so the question turns entirely on which bucket each falls into.
- Question 23.4.B.1, 3.4.B.4
Once the gym is open, which of the following recurring costs is best classified as a direct cost?
- A.The office manager's salary for handling memberships and billing.
- B.The wages of the route setters who build the climbing routes.
- C.The monthly premium on the gym's liability insurance policy.
- D.The gym's monthly spending on advertising and promotion.
Check answerHide answer
Answer: B
- A.
- The bait is the assumption that all wages are direct. Wages classify by the job, and office and sales staff sit in operating expenses; the office manager runs the business around the product without ever touching a route.
- B.
- Correct. Direct costs are tied to producing or delivering the specific good or service a business sells, and what Crux House sells is climbing. The route setters build the product itself, so their wages are direct labor. A service business collects its direct costs under the name cost of sales: direct labor, travel, and the materials used to deliver the service.
- C.
- A classic indirect cost: the premium is a bill for running the business that no single climb can claim.
- D.
- A classic indirect cost: advertising promotes the business as a whole, and no single climb can claim the spend.
- Question 33.4.B.2
As monthly visits at Crux House grow, which conclusion about the gym's recurring costs is best supported?
- A.Recurring costs at the gym will rise in proportion to monthly visits.
- B.The warehouse rent will rise as more climbers crowd the leased space.
- C.Chalk, tape, and cleaning spray rise with visits while rent and the premium hold.
- D.The liability premium is variable, because more climbers raise claim risk.
Check answerHide answer
Answer: C
- A.
- The rent alone disproves it. A fixed expense holds its number whatever the turnstile counts, so a claim that sweeps in the whole cost list fails on the lease before it reaches the chalk.
- B.
- The lease sets the rent, and the number holds whether ten climbers or a thousand walk in each month. A fixed expense does not move with service levels, and rent is the textbook example.
- C.
- Correct. Variable expenses increase as production or service levels increase, and every visit consumes chalk, tape, and cleaning spray, so those lines track the visit count. Fixed expenses do not change with service levels; the lease sets the rent and the policy sets the premium, whatever the turnstile says.
- D.
- The risk logic is true: more climbers probably do make a claim more likely. Classification ignores that. Fixed or variable describes what the bill does this month, and the premium is set by the policy contract, the same number in a slow month and a packed one; if the insurer raises the rate at renewal, the gym simply gets a new fixed number.
- Question 43.4.B.2, 3.4.B.3
A furniture workshop builds wooden chairs in a rented production building. Which of the following best describes the rent on that building?
- A.A fixed cost, because the bill holds steady inside cost of goods sold.
- B.A variable cost, because the rent bill recurs each month of production.
- C.An operating expense, because rent on a building is an indirect cost.
- D.A one-time startup cost, because the lease was signed before opening.
Check answerHide answer
Answer: A
- A.
- Correct. Producers of goods call their direct costs the cost of goods sold, and COGS holds four kinds of spending: raw materials, production supplies, production wages and benefits, and the cost of operating the manufacturing facility. Rent on the production building is facility cost, so it sits inside COGS, and it is fixed, the same bill whether the shop builds ten chairs or two hundred. The tested nuance: COGS components can be either fixed or variable, the factory rent fixed while the lumber bill rises with every chair.
- B.
- This swaps the definitions. Variable means the amount moves with output, and a steady monthly bill is exactly how a fixed cost behaves.
- C.
- This turns one true case into a rule. Classification follows what the space does: rent for a factory is fixed and sits inside cost of goods sold as facility cost, while a climbing gym's rent is indirect. This building is the production line.
- D.
- Signing before opening does not make a cost one-time; the lease keeps billing every month the workshop operates. One-time startup costs are the fees paid exactly once, like incorporation and licensing.
- Question 53.4.A.2, 3.4.A.3
Crux House Startup Costs
Andre itemizes the launch, and the table shows the numbers.
Item | Amount Incorporation and licensing fees | $1,200 Climbing walls, padding, and fixed equipment | $60,000 Lease deposit | $8,000 Opening stock of rental gear | $6,000 Opening marketing | $4,800 Total | $80,000 Which conclusion is supported by the table?
- A.Once the gym opens, its operating expenses will run 18,800 dollars per month.
- B.The fees and the walls, 61,200 dollars of the total, will not recur after launch.
- C.The 60,000-dollar climbing wall purchase will appear as cost of goods sold in year one.
- D.The 8,000-dollar lease deposit means the gym's monthly rent will be 8,000 dollars.
Check answerHide answer
Answer: B
- A.
- This reads the 18,800 as a monthly figure, and the table shows launch spending only; the categories continue after opening, while the launch amounts do not repeat as written.
- B.
- Correct. Sort the table into the two startup buckets. The incorporation and licensing fees and the wall and equipment purchase are one-time expenditures: 1,200 plus 60,000 is 61,200, and neither line bills again. The remaining 18,800, the deposit, the gear, and the marketing, sits in the initial-expense bucket, the categories that keep billing after opening: the deposit turns into monthly rent, the opening stock becomes reorders, the launch campaign becomes an advertising budget.
- C.
- The walls are equipment, a one-time expenditure, and COGS belongs to producers of goods. A climbing gym sells a service, and a purchase of long-lived fixed equipment is not the direct cost of any year's sales.
- D.
- This imports a habit from outside the table. Deposits often equal one month of rent at some businesses, and nothing in this table states the gym's rent, so a supported conclusion uses only what the table shows.
- Question 63.4.B.6
Two food truck owners in the same city each carry the workers compensation insurance required for their employees. One also buys an optional policy covering equipment damage; the other declines it and keeps the premium. Which of the following best explains the difference?
- A.The owner who declined is operating illegally until equipment coverage is bought.
- B.The owner who bought the policy expects the payouts to exceed the premiums paid.
- C.The owners differ in how much risk they will hold, so optional coverage differs.
- D.Equipment coverage is an operating expense, while workers compensation is not.
Check answerHide answer
Answer: C
- A.
- This stretches the required label over an optional policy. The law compels workers compensation here, and equipment coverage stays a choice.
- B.
- This invents a motive insurance does not promise. A policy buys protection from a large loss, and in most years the premium buys nothing at all, on purpose.
- C.
- Correct. Insurance exists to protect against financial losses from accidents, injuries, and property damage, and coverage splits into required and optional. Workers compensation is the standard example of required coverage, so both owners carry it. Everything past the requirement is a judgment call, and businesses vary in how much risk they will hold versus how much premium they will pay to move risk onto an insurer. Same city, same trucks, different risk tolerance, both legal.
- D.
- Both premiums are operating expenses once paid, so the classification cannot separate the owners. The difference the question asks about is the decision to buy optional coverage at all, and that is a risk-tolerance call, not an accounting category.
In a class? These questions are not recorded.
Take the same questions as a scored quiz and your teacher will see that you have finished this section.
Take the scored quiz →6 Common Mistakes on 3.4
The wrong moves students actually make on these questions, why each one is wrong, and what to do instead. Part of the practice tier.
See what is includedCED Codes
3.4.A.1 · 3.4.A.2 · 3.4.A.3 · 3.4.B.1 · 3.4.B.2 · 3.4.B.3 · 3.4.B.4 · 3.4.B.5 · 3.4.B.6